
CTA longs leave room for further diesel selling
Planned G7 stock releases have pressured Gasoil and triggered CTA selling, while sizeable remaining longs leave further downside flow risk if Q4 fundamentals soften.
European Gasoil prices and structure came under pressure after the G7 announced up to 100 mbbl of diesel and crude stock releases over the next four months (see here and here). The scale is material versus ~24 mbbl of extra-regional European imports in September. A front-loaded diesel release should pressure prompt structure, though contango still looks unlikely given persistent global diesel tightness.
CTAs responded quickly to the bearish pressure following the announcement. On Oct 2, Trend-following CTAs sold ~4.5 mbbl of European Gasoil outright and ~2.3 mbbl across Gasoil time spreads (barrel equivalent of spread exposure), including M1/M2, M1/M3, M2/M3 and the quarterly spread. Further selling followed on Oct 5, with ~0.5 mbbl sold in M1/M2. The impact was more limited in ULSD, where only ~0.2 mbbl were sold in M1/M2, consistent with the release being primarily focused on the European market.
The broader diesel balance remains tight. Russia’s export ban runs through October, while Middle Eastern gasoil/diesel exports still lag the recovery in crude flows. Meanwhile, the G7 release reduces the risk of a US diesel export ban. US exports have reached seasonal highs in every month this year and averaged 1.3 mbd YTD, making them crucial amid Russian and Middle Eastern supply disruption.
The next key risk is the potential return of Russian diesel exports in Q4. Kpler Insight does not currently expect the ban to be extended beyond October, with domestic fuel stocks apparently recovering during September. Renewed Russian flows, typically directed toward Brazil, Turkey and North Africa, could add further pressure to flat price and prompt structure, potentially triggering additional CTA selling. Trend-following CTAs still hold 13.4 mbbl long in Gasoil and 12.4 mbbl in ULSD, leaving meaningful downside flow risk. By contrast, selling capacity is already more limited in Gasoil spreads, with CTA exposure at -75% short in M1/M2, -50% short in M1/M3 and flat in M2/M3, while ULSD spreads remain less bearish at -12.5% short in M1/M2, flat in M1/M3 and 25% long in M2/M3.
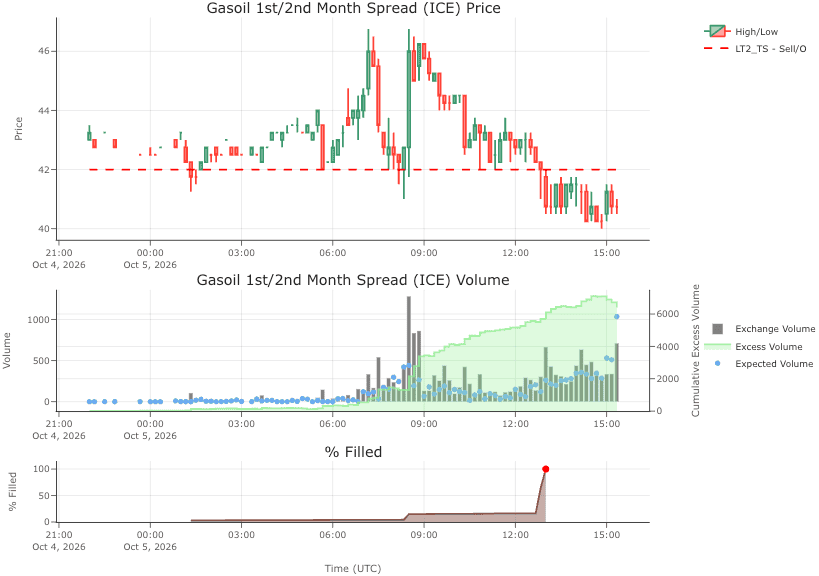
Source (all charts): Kpler Financial Flows
This report draws on Kpler Financial Flows. The full dataset delivers daily and intraday CTA positioning, order stacks, and flow estimates - allowing you to track systematic moves as they develop, rather than after the fact.

See why the most successful traders and shipping experts use Kpler