
VLCC freight may have peaked, but Hormuz keeps the floor high
Tanker freight from the Mideast Gulf hit record levels last week, with VLCC rates pushing $32/bbl, equivalent to earnings of $1.2m/day. These unprecedented rates have been supported by exceptionally strong Asian refining margins, allowing refiners to absorb sharply higher transportation costs.
Rates now appear to have peaked for the time being as Asian product cracks cool. We expect freight to ease further from recent highs but remain elevated. Additional crude moving through the Strait of Hormuz will increase logistical constraints and reduce effective vessel availability, partly offsetting the decline in ton-mile demand caused by lower Sidi Kerir flows.
Market & Trading Calls
- VLCC freight: Bearish from record highs, but rates should remain well above pre-war levels as Hormuz congestion and operational constraints tighten effective vessel supply.
- Asian refining margins: Remain resilient despite record freight costs, leaving refiners with capacity to absorb elevated tanker rates.
- VLCC demand: Lower Sidi Kerir flows reduce ton-mile demand, but the impact will be offset by rising Saudi East Coast exports and greater inefficiencies around the Strait of Hormuz.
Resilient margins
The record-breaking rise in freight means transportation is now a major component of refining economics. At the end of last week, VLCC freight from the Mideast Gulf to Asia accounted for 21% of the Gross Product Worth (GPW) of Basrah Medium. GPW represents the theoretical value of a crude oil’s refined products at prevailing market prices. This compares with an average of 4% over the six months before the start of the war in February.
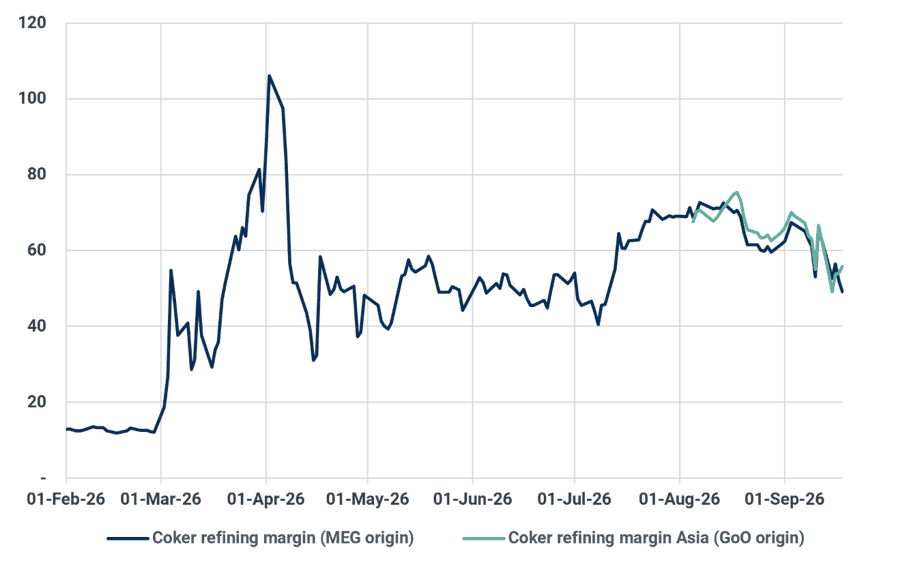
The difference between a crude’s GPW and its crude price plus freight provides a simple measure of refining margins. As shown below, surging VLCC freight compressed Eastern Asian coking margins last week, but the impact remained relatively limited. Basrah Medium margins for barrels shipped directly from the Mideast Gulf fell from $62/bbl to $49/bbl as stronger Asian product cracks insulated refiners from higher transportation costs.
The economics are similar for crude shipped directly from the Mideast Gulf, where barrels are more heavily discounted to compensate for higher freight, and cargoes transferred ship-to-ship (STS) in the Gulf of Oman, where freight is around $10/bbl cheaper.
Eastern Asia coker refining margin calculation basis MEG loaded Basrah Medium $/bbl
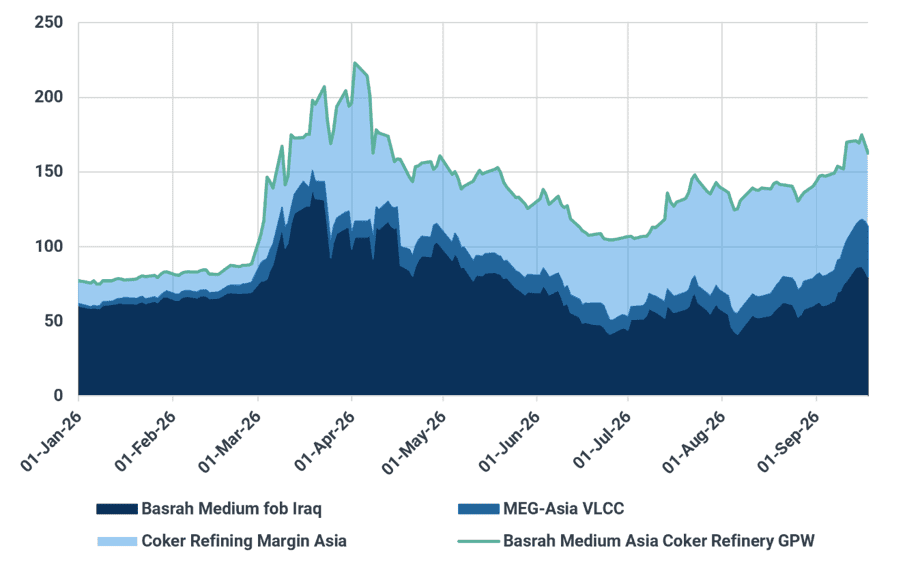
Source: Kpler, Argus Media
Eastern Asia coker refining margin calculation basis Gulf of Oman loaded Basrah Medium $/bbl
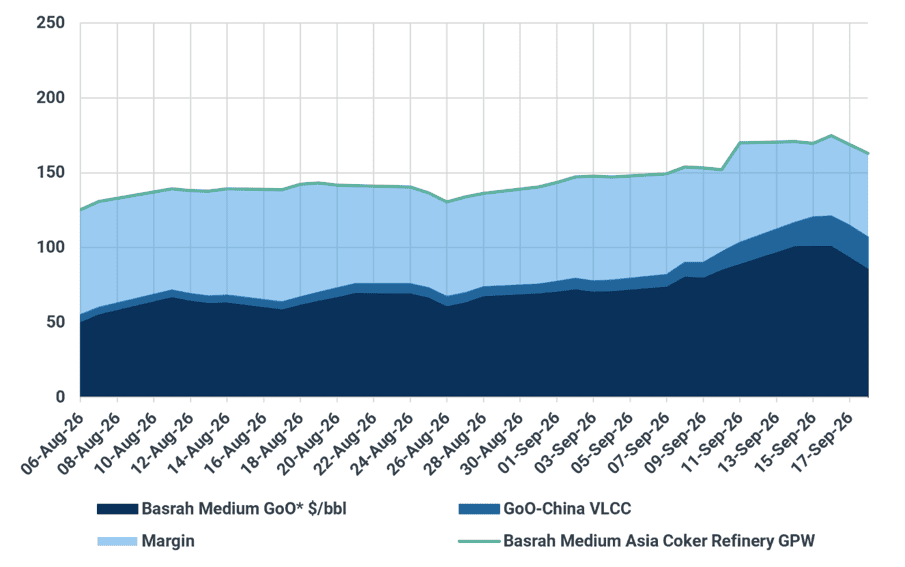
Source: Kpler, Argus Media
Based on current product cracks and crude prices, Persian Gulf-to-Asia freight could theoretically more than double to $60/bbl before refining margins are fully eroded. Such levels are highly unlikely, however. Refiners would probably reduce crude purchases before delivered costs pushed margins below $10–15/bbl.
Eastern Asia coker refining margin basis Basrah Medium (MEG and Gulf of Oman load) $/bbl
Source: Kpler, Argus Media
Lower ton-miles, tighter logistics
After Houthi attacks on Saudi-linked vessels began in July, 1.3 Mbd of crude was shipped north in August on VLCCs via the Sumed pipeline or directly through the Suez Canal. The diversion significantly increased ton-miles, offsetting much of the tanker demand lost within the Mideast Gulf, where exports remained 65% below pre-war levels.
Attacks on the East-West pipeline have now severed this route, removing 2-4 Mbd of crude from the Red Sea and Mediterranean and affecting VLCC, Suezmax, and Aframax demand into Europe. Saudi Arabia has instead sharply increased exports from its East Coast, requiring additional transit through the Strait of Hormuz, the chokepoint the East-West pipeline had previously allowed Saudi barrels to avoid.
Saudi Arabia was one of the last Gulf producers to rely on shuttle tankers to increase exports through Hormuz because its Red Sea outlet reduced the need for them. However, STS capacity in the Gulf of Oman is reportedly operating at or close to maximum capacity, making alternative export arrangements less efficient.
Purely on ton-miles, the shift is negative for VLCC demand. A Sidi Kerir-to-Ulsan voyage generates 58% fewer ton-miles than Ras Tanura-to-Ulsan. Replacing the tanker demand generated by 1.2 Mbd of Sidi Kerir-to-Asia exports would therefore require Ras Tanura flows to rise to 2.9 Mbd, a 138% increase.
Early indications show Saudi Arabia is rapidly increasing East Coast loadings. As of 21 September, six VLCCs are loading at Ras Tanura, the highest days of loadings since the war started.
VLCC rates do not need this additional volume to fully replace lost Sidi Kerir ton-miles to remain elevated. The increasingly constrained logistics of moving more crude through Hormuz, combined with limited STS capacity in the Gulf of Oman and greater operational risk, should reduce effective vessel availability even as headline ton-mile demand falls. We therefore expect rates to retreat from last week’s extreme highs but not normalize. The loss of the Red Sea route shifts the source of tanker tightness from distance to inefficiency.

See why the most successful traders and shipping experts use Kpler