


Delicately balanced
The USGC refining system has quietly been doing some heavy lifting. Strong US production has kept European import volumes healthy while simultaneously absorbing demand from Latin American and African buyers displaced by renewed drone strikes on Russian export infrastructure. For now, flows work and the barrels are moving. But this is a thin margin of comfort. The transatlantic arb is sensitive to freight, refinery run rates, and crack spreads that can shift fast. A tumultuous USGC hurricane season could close this window quickly. The market is balanced, not buffered.
Market & Trading Calls
Gasoil/diesel
- Slightly bearish WoS: Strong USGC output is keeping European import volumes healthy while simultaneously allowing US refiners to absorb Latin American and African demand affected by renewed drone strikes on Russian export infrastructure.
- Slightly bullish EoS: The NDRC's formalized run-cut floor — 80% of year-ago output — makes a large July Chinese export program unlikely, keeping regional supply tight until South Korean refiners clear maintenance and return to full run rates.
Jet/kero
- Slightly bearish EoS: Above-trend US production and healthy PADD 5 arrivals from elsewhere have reduced Asian outflows, keeping the region largely self-sufficient. Price-responsive demand reduction has done the rest of the rebalancing work.
- Neutral WoS: Airline and refiner assurances of adequate summer supply, backed by high continent-wide production, have taken the sting out of spot prices near-term.
Middle Distillates S&D
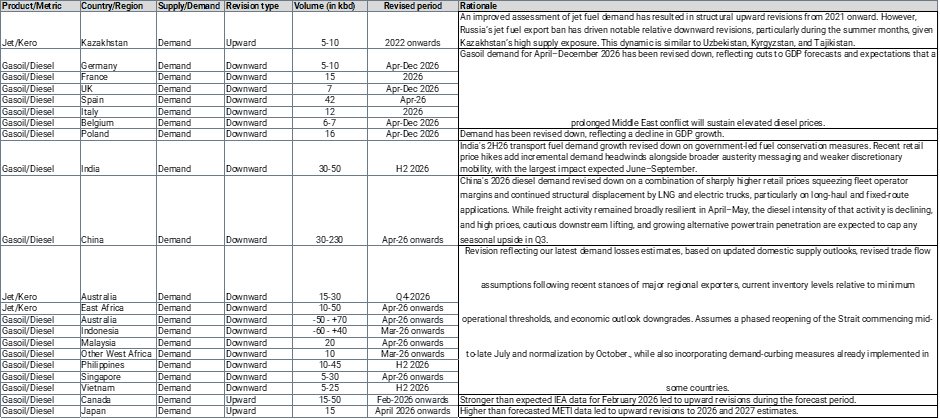
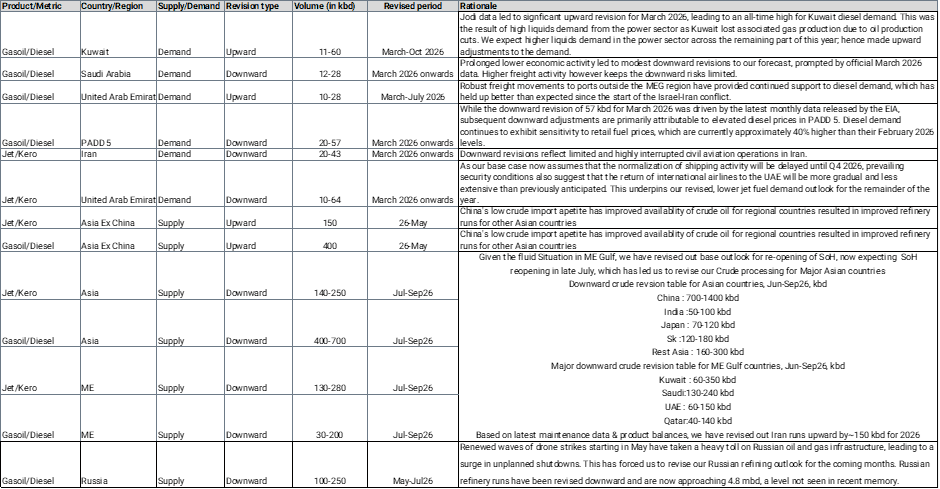
Table of Supply and Demand revisions
Source: Kpler
Global middle distillate balances have tightened further in our June outlook edition, by ~680 kbd for June–September versus the previous edition. The tightening is overwhelmingly supply-driven, following downward revisions to crude run assumptions across Asia, the Middle East and FSU East after incorporating our updated de-escalation scenario into our refinery outlook, which now assumes a phased reopening of the Strait commencing mid-to-late July and normalization by October, instead of September.
Delving deeper into gasoil balances, during the summer months, balances are expected to tighten by an average of ~1070 kbd versus last year, expectations of lessened supply from the Middle East and Asia (mainly China) as the conflict drags on have been juxtaposed with a worsening supply outlook from Russia.

See why the most successful traders and shipping experts use Kpler






