

The new geopolitics of refining
The conflict with Iran has exposed a critical gap in traditional energy security strategy, demonstrating that refining capacity—not crude supply—has become the more immediate geopolitical vulnerability. While crude markets have largely stabilized, constrained refined product markets leave gasoline prices vulnerable and challenge long-held assumptions about energy resilience.
The New Geopolitics of Refining
For decades, energy security has centered on crude oil. Governments built large strategic petroleum reserves for crude, protected critical shipping lanes, and focused diplomacy on keeping oil flowing to global markets. Five months into the conflict with Iran, the market is pointing to a different reality. The world's greatest energy vulnerability is no longer simply producing enough crude oil—it is maintaining enough refining capacity to turn that crude into gasoline, diesel, and jet fuel.
Markets have repeatedly been told the war is over, a deal is imminent, or diplomacy is back on track. Yet despite the rhetoric, tanker traffic through the Strait of Hormuz remains only a fraction of what it was before February. The recent return to hostilities underscores why shipowners never fully regained confidence in the route.
The decline in crude prices has reinforced the perception that the energy crisis has largely passed. That interpretation risks focusing on the wrong indicator. Crude markets have adjusted far more quickly than refined product markets, suggesting that the strategic bottleneck has shifted downstream.
The memorandum of understanding (MOU) removed much of the geopolitical risk premium and pushed crude prices back toward pre-war levels. In reality, however, the crude market had already begun rebalancing before the ink on the agreement was dry. China's decision to sharply reduce crude imports effectively returned millions of barrels per day to the global market. Releases from the US Strategic Petroleum Reserve added further supply. Together, those developments restored more than 7 million barrels per day to the global balance and largely resolved the crude shortage.
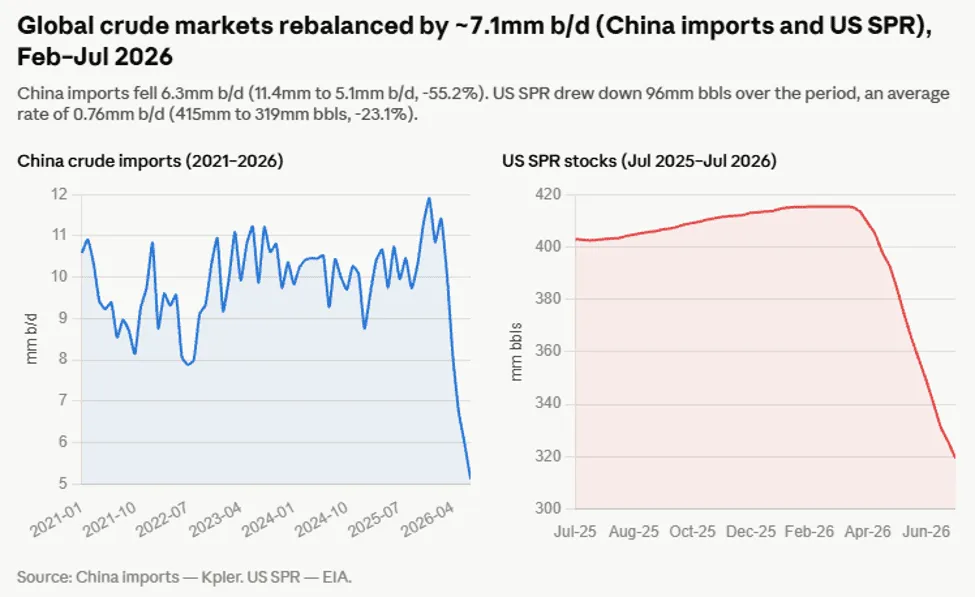
While crude found relief through weaker Chinese buying and strategic government stock releases, gasoline, diesel, and gasoil faced a very different reality. Rather than gaining supply, the global market lost refining capacity. Repeated Ukrainian drone strikes have significantly reduced Russian refinery operations, while conflict-related disruptions across the Middle East have constrained another important source of refined product exports. Higher prices have tempered demand, but not enough to offset those supply losses.
The mismatch between crude and refined products exposes a gap in today's energy security framework. Governments have spent decades preparing for disruptions to crude oil supplies, yet they have far fewer tools available when the constraint is refining capacity. The geopolitical risk has not disappeared; it has migrated from crude supply to the refining system. Crude prices dominate headlines and shape perceptions of energy security. Meanwhile, stresses in refined product markets build quietly until they emerge as higher gasoline and diesel prices. By the time those pressures become politically visible, governments have far fewer options available to respond.
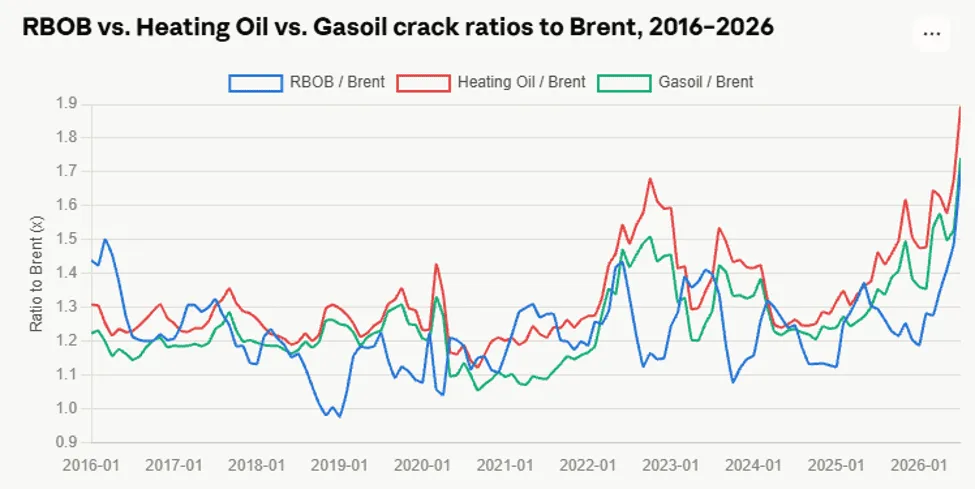
Financial markets are already reflecting that shift. RBOB, heating oil, and gasoil continue to trade at historically large premiums to Brent crude. They suggest that the scarcity is no longer crude oil itself, but the capacity to transform it into usable fuels. In other words, markets are signaling that refining—not crude production—has become today's strategic bottleneck.
Inventories tell the same story.
To test whether reopening the Strait of Hormuz would materially improve the outlook, I modeled global gasoline days cover under a range of reopening scenarios. Even if the Strait reopened immediately, inventories recover only marginally. Across every scenario—including an immediate reopening—global gasoline inventories remain historically tight through year-end. Days cover hovers near 25 days of demand. Reopening the Strait helps restore crude flows, but it does little to rebuild refined product inventories.

See why the most successful traders and shipping experts use Kpler






