
Weak fundamentals and growing bearish sentiment after Arctic LNG 2 cargo docked in China
Market & trading calls
European TTF front-month price outlook: Bearish as lower temperatures, strong renewable generation, and higher LNG imports are expected to outweigh the bullishness stemming from the start of the maintenance season in Norway. The news of Arctic LNG 2 cargo docking in China will likely weigh down on prices in the coming days. An upside price risk to the outlook stems from any delay or unplanned event extending Norwegian maintenance.
Asian LNG front-month price outlook: Slightly bearish as high LNG inventories, steady supply, and weak regional demand outweigh increased gas burn in China and higher LNG consumption in India.
Asian LNG – TTF spread outlook: Slightly widened as we expect a larger drop in TTF prices relative to Asian LNG prices. The spread slightly widened last week to $0.25/MMBtu on 27 August.
US Henry Hub front-month price outlook: Steady with bearish inventories, production, and demand capping upside as September contract rolls off.
Key natural gas and LNG front-month prices ($/MMBtu)
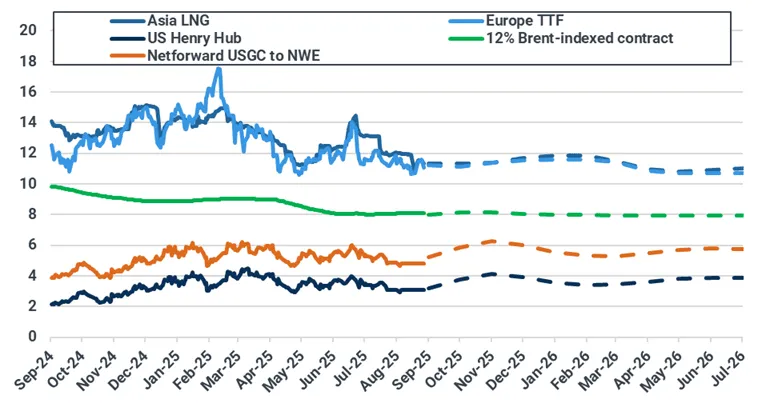
Source: ICE, NYMEX, Spark Commodities. Brent-indexed price represents 12% slope of 90-day moving average of Brent contract. Netforward USGC to NWE calculation is 115% Henry Hub contract plus shipping and regasification costs into Gate (Spark Commodities).
Asian LNG-TTF front-month spread ($/MMBtu)
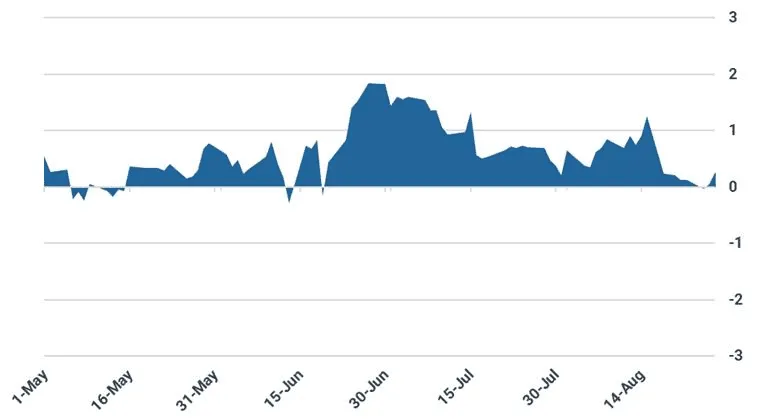
Source: ICE, Kpler Insight

See why the most successful traders and shipping experts use Kpler
Research & analysis driven by proprietary data