

Mixed global gas price signals: bearish sentiment in Asia, stable TTF and Henry Hub
Market & Trading Calls
European TTF front-month price outlook: Stable as ample pipeline supply and average renewable generation are expected to balance increased competition for LNG cargoes with Egypt and higher cooling needs. However, a risk to the outlook is posed by the unlikely possibility of US secondary tariffs on buyers of Russian natural gas and LNG.
Asian LNG front-month price outlook: Slightly bearish on robust Chinese LNG inventories, cooler Northeast Asian temperatures, and stabilized Pacific supply outweighing modest demand upside from Taiwan and South Korea
Asian LNG – TTF spread outlook: Slight narrowing as Asian LNG is expected to decline while TTF holds stable. The spread widened to $0.62/MMBtu on 6 August from $0.37/MMBtu on 30 July.
US Henry Hub front-month price outlook: Stable as projections of hot weather in mid-August are overshadowed by strong production and robust storage levels.
Key natural gas and LNG front-month prices ($/MMBtu)
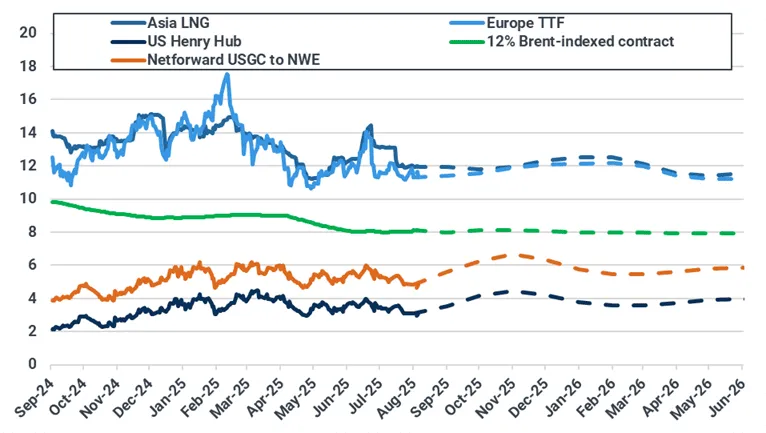
Source: ICE, NYMEX, Spark Commodities. Brent-indexed price represents 12% slope of 90-day moving average of Brent contract. Netforward USGC to NWE calculation is 115% Henry Hub contract plus shipping and regasification costs into Gate (Spark Commodities).
Asian LNG-TTF front-month spread ($/MMBtu)
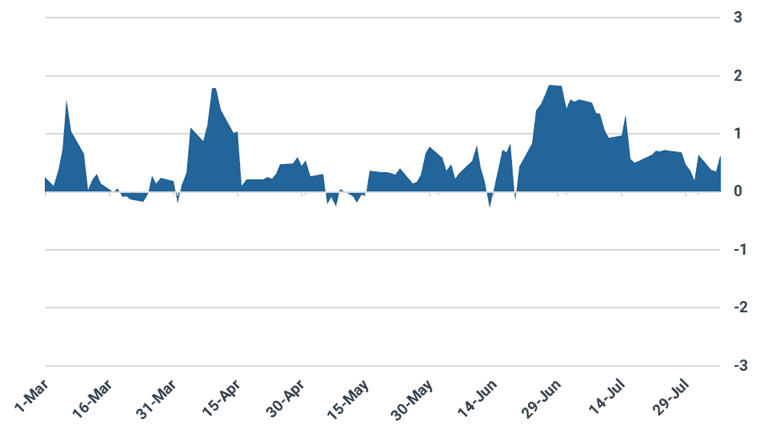
Source: ICE, Kpler Insight
Atlantic basin LNG front-month arbs ($/MMBtu)
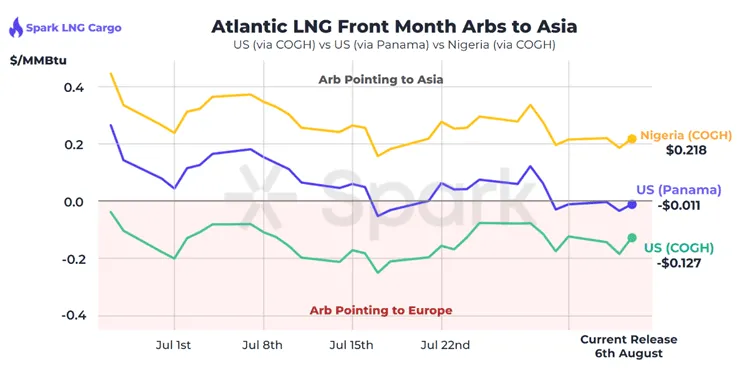
Source: Spark Commodities, incorporating ICE-listed Spark Freight and Spark Cargo products. For a full M+12 forward curve and netback cost breakdown, contact Spark at info@sparkcommodities.com.

See why the most successful traders and shipping experts use Kpler
Get research & analysis driven by proprietary data









