

Stable TTF as increasing Norwegian supply balances colder temperatures; Asian LNG pressured by ample LNG inventories and weaker Thai demand
Market & Trading Calls
European TTF front-month price outlook: Stable as a significant drop in temperatures next week will be offset by additional capacity coming online in Norway as maintenance gradually winds down. The 19th EU sanctions package on Russia, expected to be published soon, poses a risk to the outlook.
Asian LNG front-month price outlook: Slightly bearish, as elevated LNG inventories, weaker Thai LNG demand, and cooler Northeast Asian weather all pressuring prices, while Pacific supply holds steady under scheduled maintenance.
Asian LNG – TTF spread outlook: Slightly narrower as stable TTF contrasts with further downside risk in Asian LNG. The spread widened by $0.27/MMBtu to $0.24/MMBtu on 17 September.
US Henry Hub front-month price outlook: Steady as bullish momentum from revised weather forecasts showing broadly above-average temperatures for the remainder of September are counteracted by strong underground storage injections and stable production.
Key natural gas and LNG front-month prices ($/MMBtu)
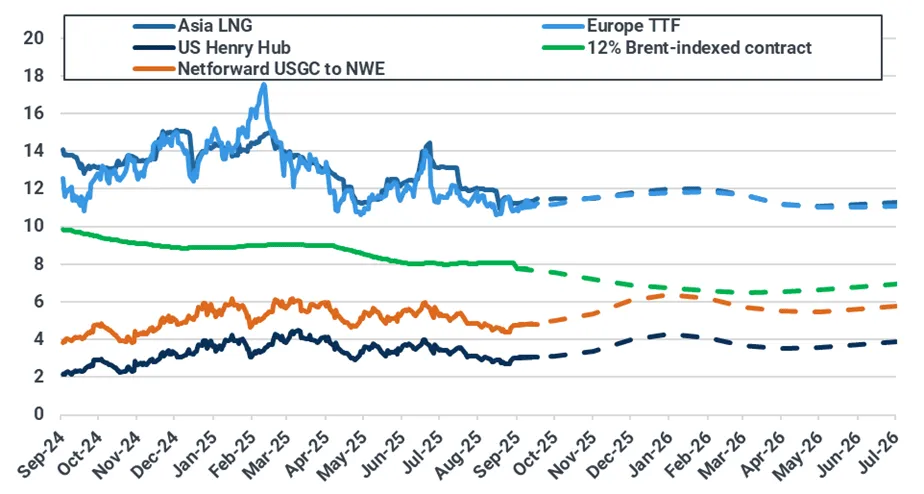
Source: ICE, NYMEX, Spark Commodities. Brent-indexed price represents 12% slope of 90-day moving average of Brent contract. Netforward USGC to NWE calculation is 115% Henry Hub contract plus shipping and regasification costs into Gate (Spark Commodities).
Asian LNG-TTF front-month spread ($/MMBtu)
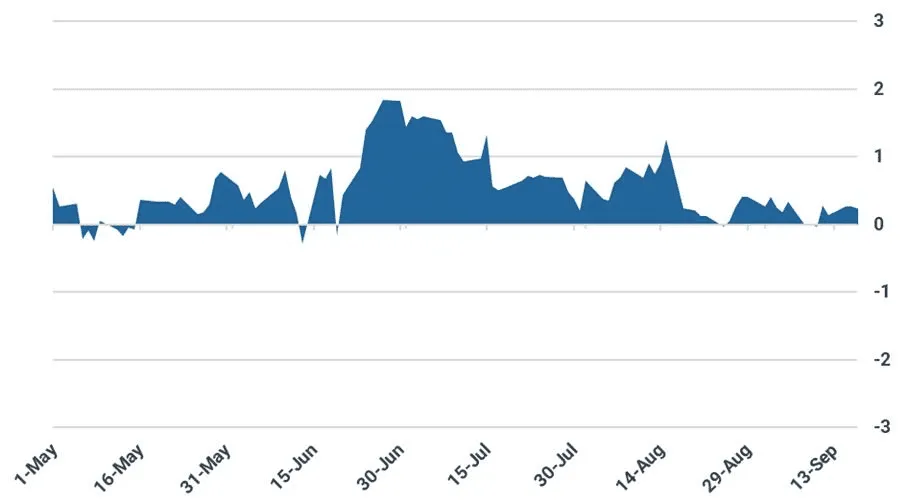
Source: ICE, Kpler Insight
Atlantic basin LNG front-month arbs ($/MMBtu)
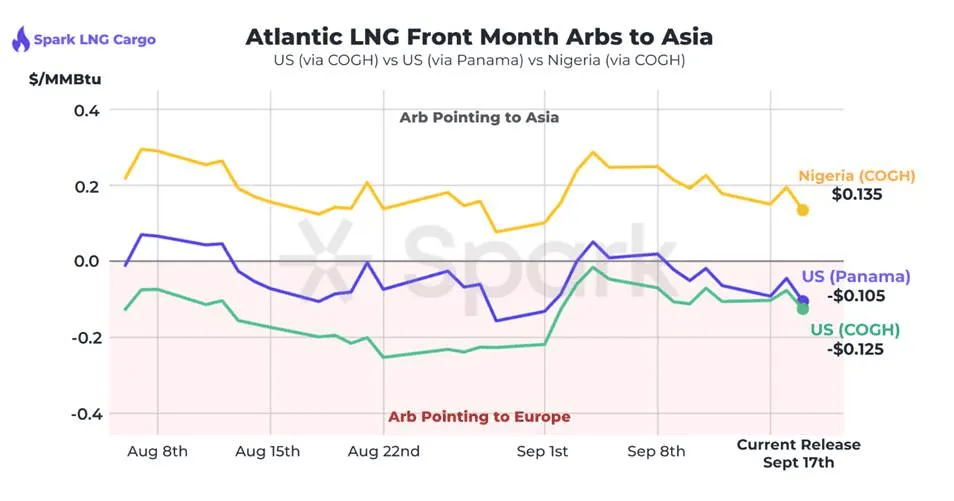
Source: Spark Commodities, incorporating ICE-listed Spark Freight and Spark Cargo products. For a full M+12 forward curve and netback cost breakdown, contact Spark at info@sparkcommodities.com.

See why the most successful traders and shipping experts use Kpler
Research & analysis driven by proprietary data









