Libya vs. Yanbu — a tug of war for Europe's barrels
As Libyan supply falters and Saudi Arabia's East-West pipeline edges back toward service, Europe's near-term crude balance hangs on which recovers control of the rope first.
Market & Trading Calls
- Long Med light sweet vs. Dated Brent. CPC, Saharan Blend and Azeri Light should stay bid even as Petroline restart headlines pressure Brent, given the scale of missing Saudi and Libyan barrels into Europe and the Med.
- A potential restart of the East-West pipeline is pressuring crude prices, but Kpler's global balance still shows a 1-2 Mbd deficit over the coming months — that underlying tightness favors buying dips over chasing the headline lower.
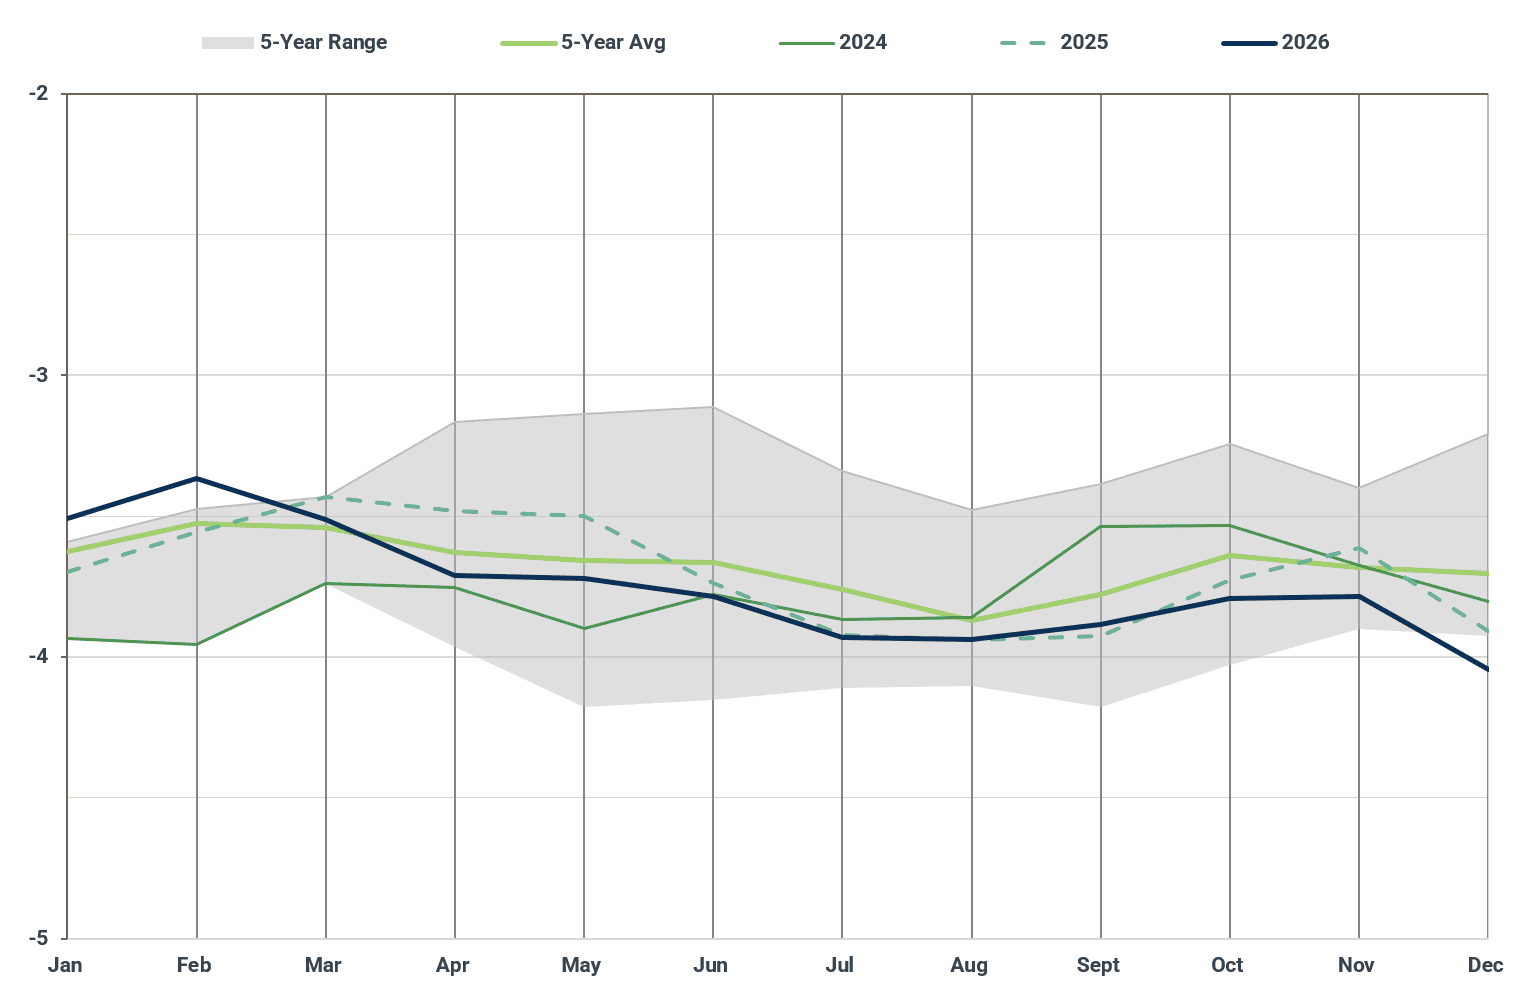
- Mediterranean crude balance to tighten more than typical in December, paving the way for tighter regional markets.
Unconfirmed reports surrounding a potential restart of Saudi Arabia's East-West pipeline have pressured crude prices on 22 September, reversing gains that had built on Libyan supply outages and a tighter global crude balance, with Brent slipping back below $100/bbl.
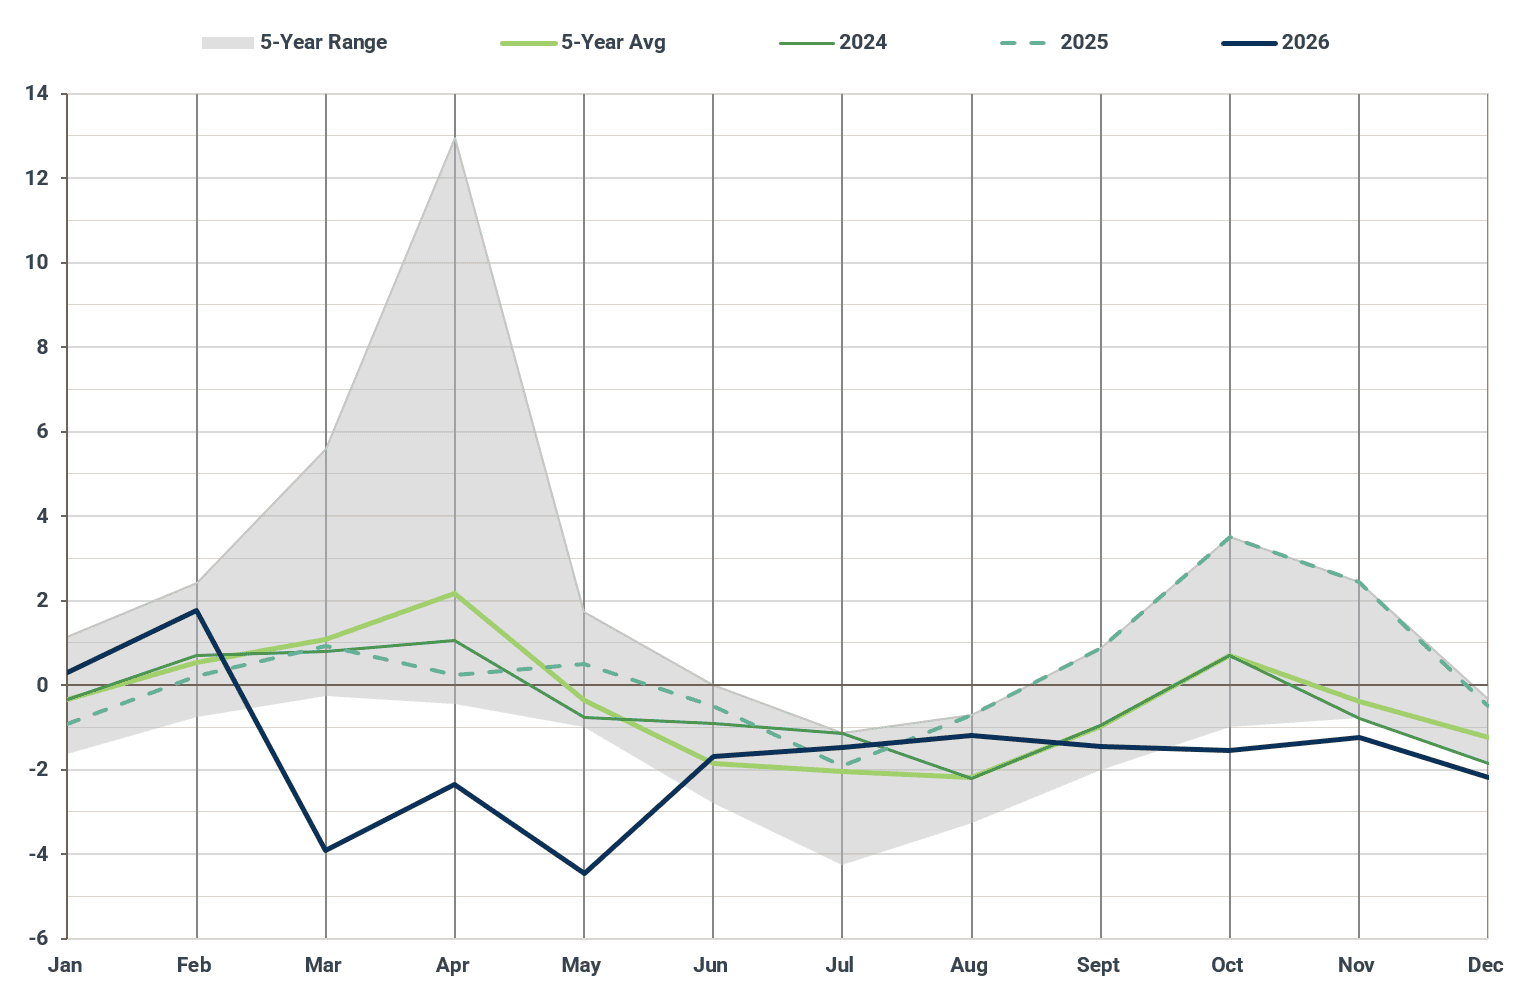
Even so, the underlying deficit in global balances continues to lend some support: Kpler's crude and condensate balance is still averaging a shortfall of 1-2 Mbd, and with SPR releases slowing, much of that draw is now coming from commercial and refinery inventories rather than strategic stocks — a dynamic that should keep prices underpinned even as rising activity from Saudi Arabia's west coast weighs in the near term.
Global crude and condensate balance, Mbd
Source: Kpler
Nevertheless, a Waha Oil leadership dispute has spilled into Zintani-led shutdowns across Libya's pipeline network, cutting flows from the 300 kbd El Sharara field to the Zawia export terminal; NOC says output has dropped sharply, technical teams cannot reach the valves, and a prolonged closure risks halting the field, shutting the Zawia refinery, and triggering force majeure. Though it is difficult to give a strict timeline for the outage, the nature of the disruptions suggests a two-to-three week halt (as an early indication).
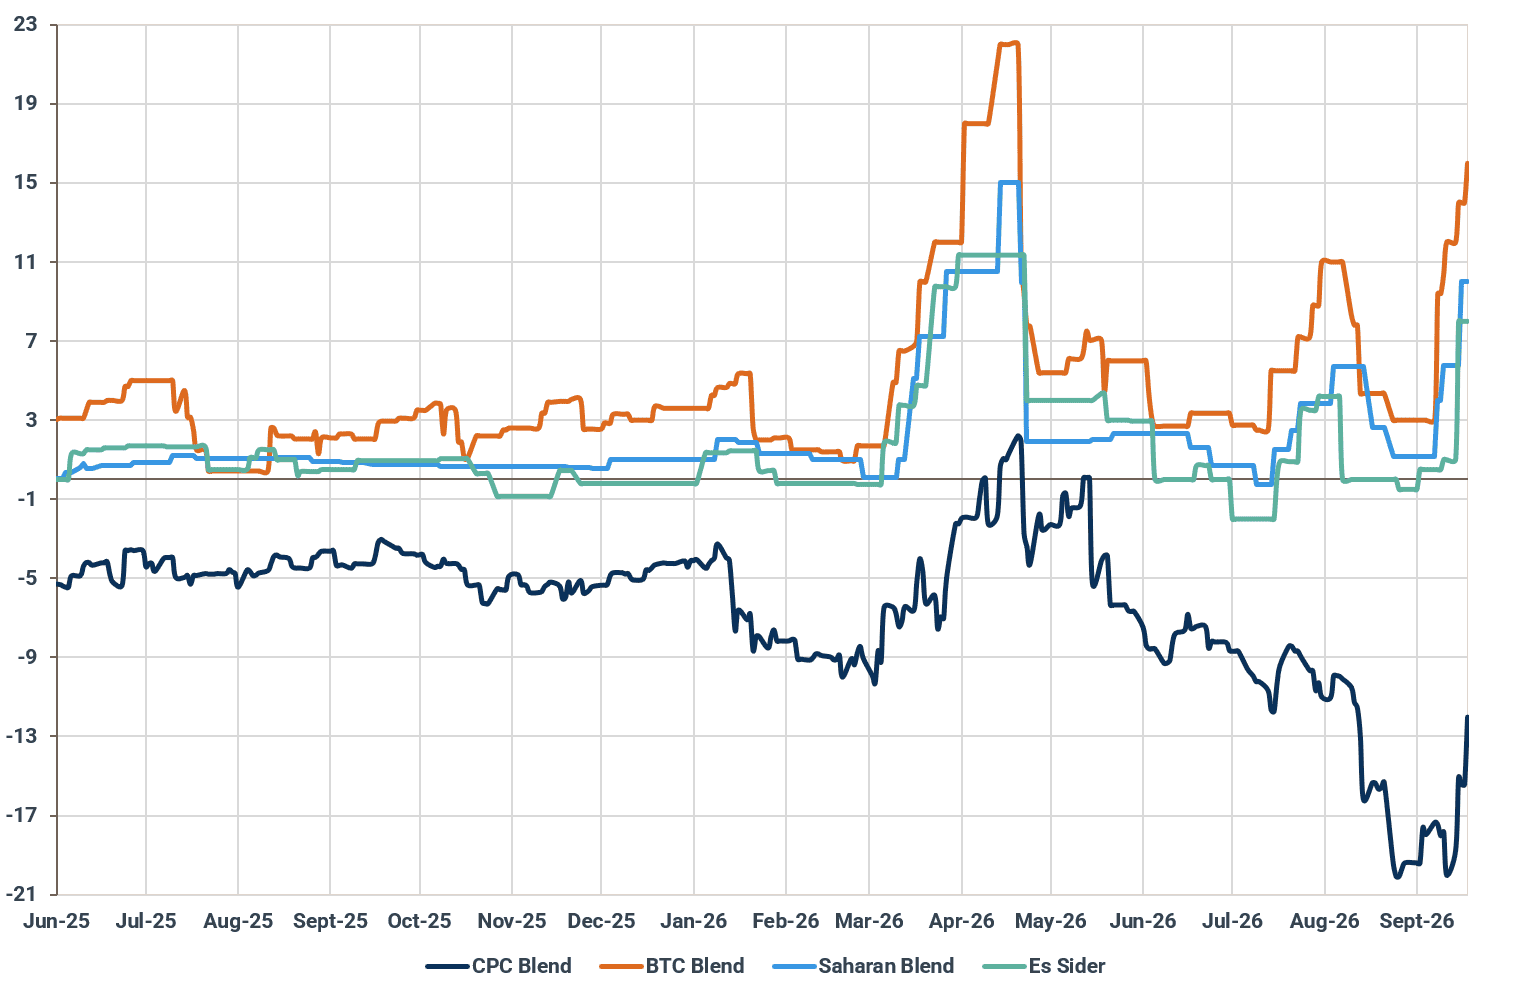
This comes at a bad time for near-term barrel availability into Europe and the Mediterranean, compounding lower Saudi flows, which should see regional crude differentials remain supported if outages persist. While there remains quality differences between Saudi Arabian and Libyan grades, with the latter being a light sweet producer, light Mediterranean grades are the most likely near-term beneficiaries since they sit closest in quality and location, with WTI Midland picking up any residual shortfall.
Mediterranean light crude differentials, $/bbl
Source: Argus Media
A potential restart of the East-West pipeline is likely to bring capacity back gradually over time. Aramco has already told European term customers they will not get any Saudi crude in October — a cutoff hitting roughly 700 kbd of normal flows into northwest Europe and the Mediterranean, with the rerouted Gulf barrels going to Asia instead.
Compounding the uncertainty, the risk of further Houthi attacks on the upcoming restored capacity remains high, leaving it unclear whether Yanbu exports will actually ramp up in the near term. Nevertheless, a potential return of Saudi crude flows from Yanbu paint a bearish picture for European and Mediterranean crude differentials into October.
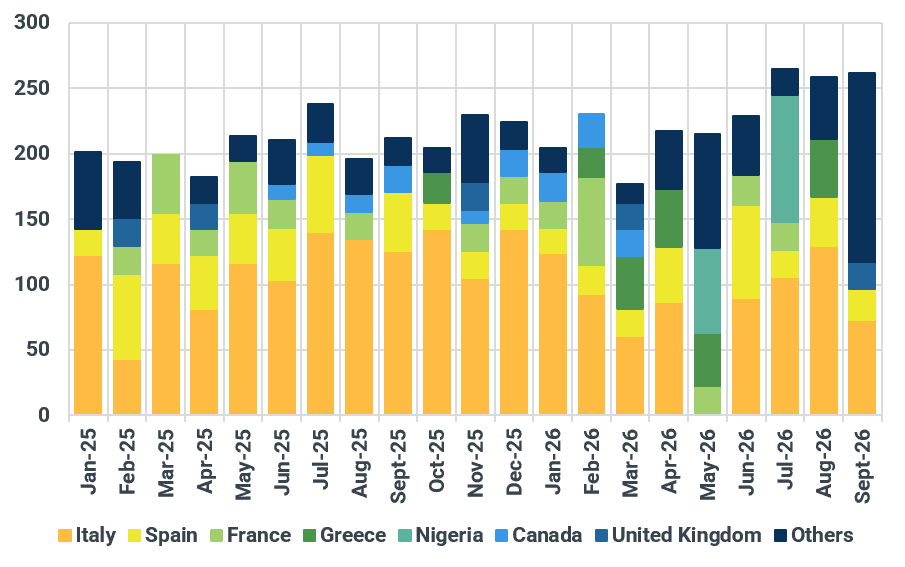
That said, the current situation leaves European refiners short of substitutes just as Libya, one of the more natural replacements for medium Saudi grades, loses supply of its own, with the impact felt disproportionately by Mediterranean refiners since almost all Sharara crude departed for the Med region in August.
Exports of Libya's Sharara by destination, kbd
Source: Kpler
This is particularly true as we head into Q4, with the Mediterranean crude balance expected to tighten more significantly towards the end of the year, keeping regional prices supported.
Mediterranean crude and condensate balance, Mbd
Source: Kpler

See why the most successful traders and shipping experts use Kpler