Crude market adapts as Mideast supply gradually returns and demand lags
Crude markets are increasingly adapting to recent geopolitical and operational disruptions as Hormuz transit recovers, Canadian outages prove temporary, and Russian refinery runs rebound. However, weak Chinese buying and ample replacement barrels from the Americas are preventing tighter physical balances from translating into sustained strength across global crude differentials.
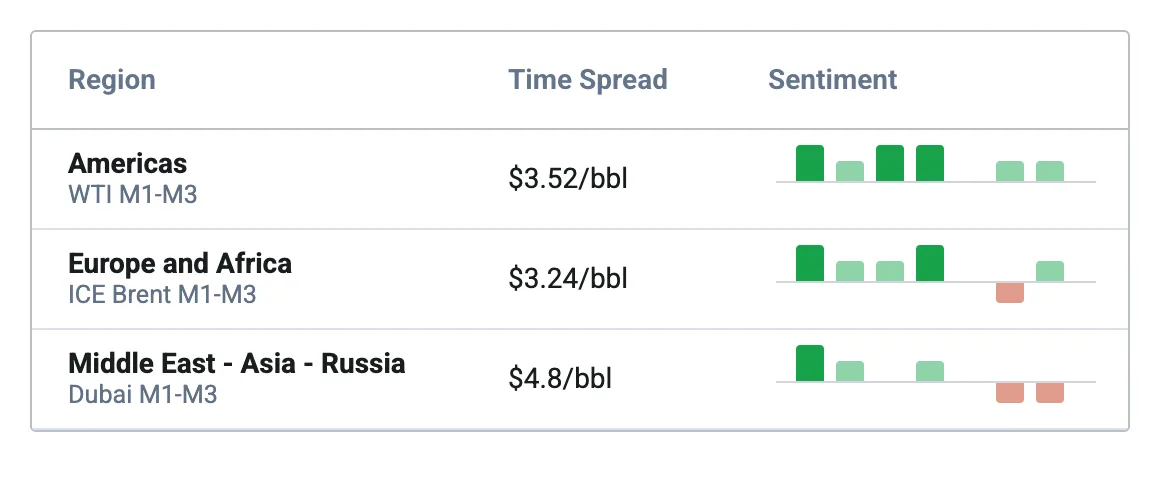
Market Calls
Executive Summary
Americas:
- Pessimistic on Canadian supply throughout summer with extreme weather forecasts likely to continue and cause disruptions
- Optimistic on medium-term Canadian exports due to rapid work on tackling several infrastructure pinch points
- Slightly bullish on Medanito differentials with Cushing tank bottoms nearing, suggesting that less WTI will be available for seaborne export
Europe and Africa:
- Expected increase in Russian refinery runs of 350 kbd between May to July as various refineries complete maintenance after drone attacks.
- Stable on elevated LatAm crude flows to EU-27 in June as the Strait of Hormuz blockade shows no signs of resolving.
- Decrease expected for EU-27 crude inventories in July/August from current levels of 365 Mbbls amid peak summer demand.
Middle East, Asia and Russia:
- Bearish Dubai timespreads. Rising non-Iranian transit through the Strait of Hormuz and accelerating UAE production recovery are increasing prompt crude availability, easing immediate supply concerns.
- Bearish Murban-Dubai. Most of the incremental UAE exports consisting of Zakum crude, demand for the grade will narrow its spread against Murban.
- Neutral to slightly bearish Russian crude diffs into Northeast Asia. Chinese state-owned refiners remain reluctant buyers of Saudi crude despite a $6/bbl reduction in July OSPs, while Russian grades and Atlantic Basin alternatives continue to offer a significant delivered-cost advantage.
Americas: Extreme weather and Cushing levels could topple fragile balance
Extreme Canadian weather finally hits supply
Extreme weather events in northeastern Alberta, encompassing wildfires, flooding, and thunderstorms, have triggered critical power outages and forced Cenovus Energy to declare force majeure at its two largest oil sands assets. The disruption struck the Foster Creek and Christina Lake facilities last week, curtailing an estimated 4% of the firm’s bitumen output.
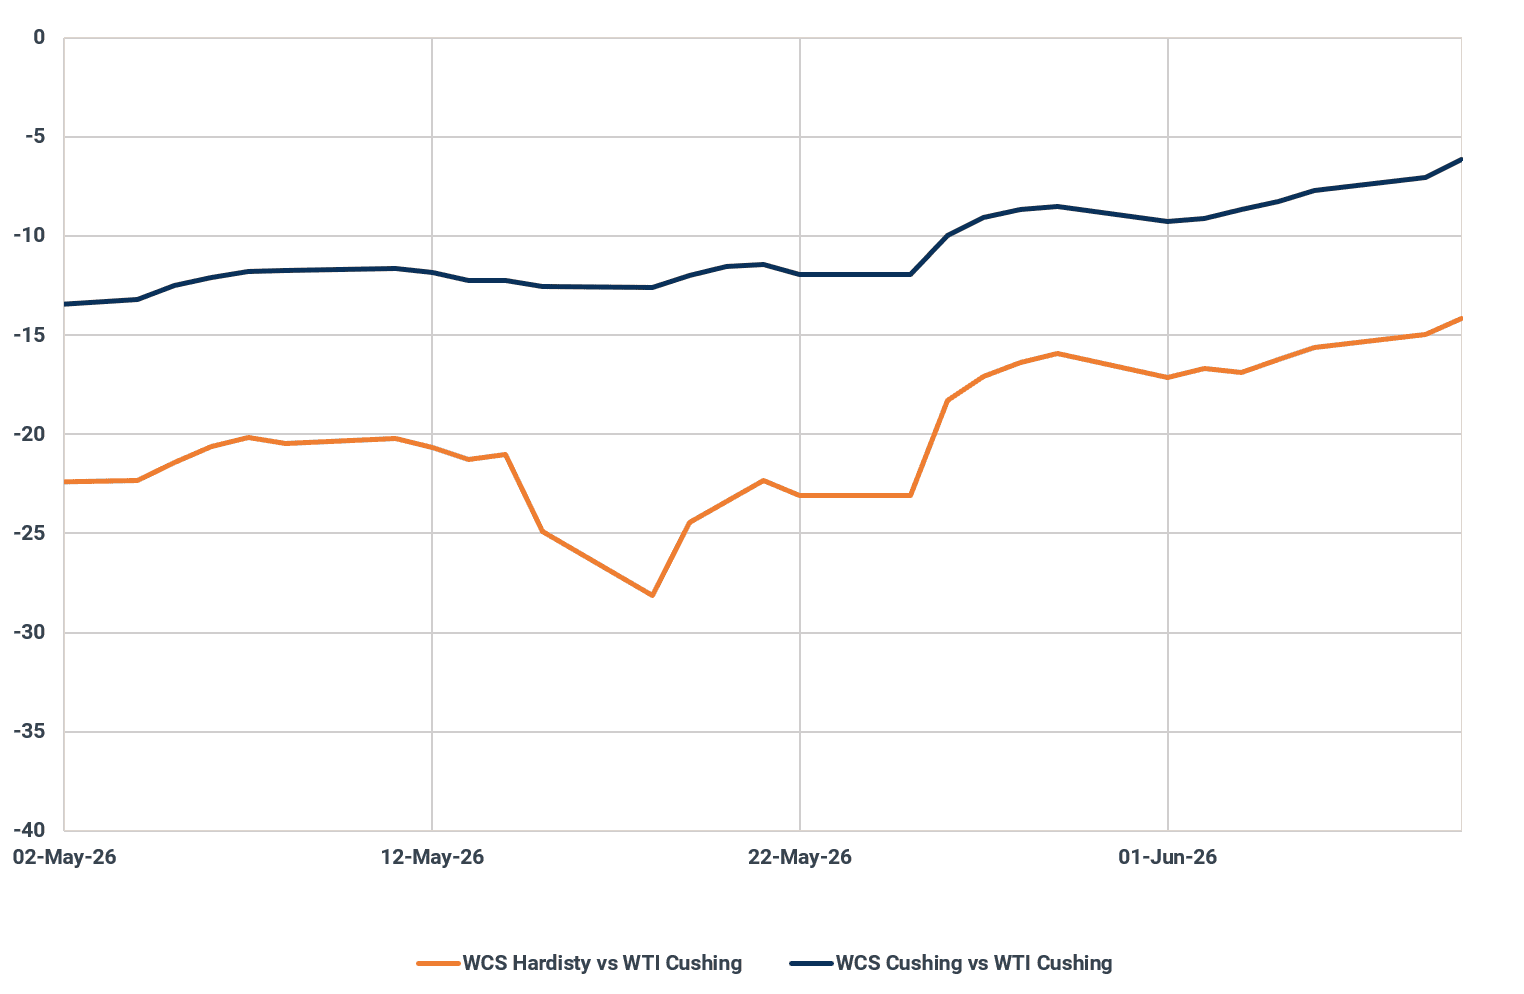
This sudden supply shock has aggressively tightened Canadian heavy sour balances, driving a sharp pricing divergence across the complex. The July-delivery Western Canadian Select (WCS) discount at Hardisty surged to around $12/bbl under the July CMA Nymex, hitting a three-month high (Argus Media). Concurrently, WCS at Houston narrowed to a near $2.70/bbl discount.
Conversely, this bitumen curtailment has entirely crushed regional condensate demand. With producers requiring significantly less diluent for blending, excess condensate is flooding the spot market. Consequently, Fort Saskatchewan condensate collapsed to a near $9/bbl discount against July Nymex, marking its lowest valuation since June 2022 (Argus Media). While recent heavy rains have brought all regional wildfires under control, the timeline for Cenovus' full operational recovery remains opaque, warranting a strictly bullish short-term outlook for heavy Canadian differentials.
WCS crude differentials to WTI, $/bbl
Source: Argus Media
Canada focusing on infrastructure projects to boost exports
Canada is actively advancing critical infrastructure projects to maximize the export viability of its heavy crude, primarily focusing on marine logistics out of British Columbia.
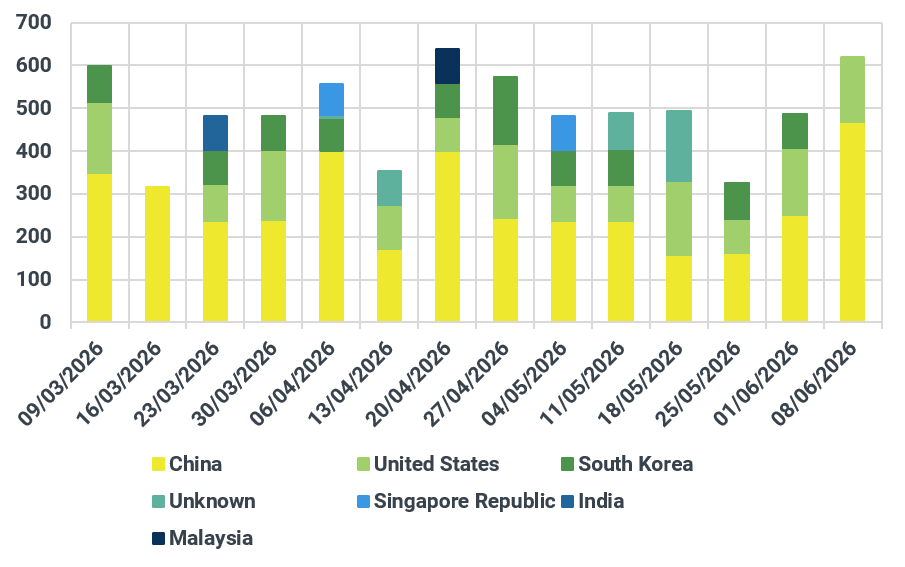
The Vancouver Fraser Port Authority aims to commence essential dredging operations near the Second Narrows Bridge by late summer, contingent on final federal and environmental permits following a March public engagement phase. Currently, Aframax vessels loading at the Westridge Marine Terminal, which is fed by the newly expanded 890 kbd Trans Mountain system, are severely restricted by tide and draft limits, capping loadings at 550-600 kbbl.
The proposed dredging will unlock the ability to fully load these tankers up to 750 kbbl, fundamentally transforming the voyage economics for long-haul arbitrage flows into the Asia-Pacific basin.
In tandem with these port optimizations, Trans Mountain secured regulatory approval on 4 June for a 10% capacity expansion. By deploying drag-reducing agents, the federally-owned pipeline operators intend to inject an additional 90 kbd of throughput capacity as early as January 2027. In the immediate term, the recent upstream production curtailments across Alberta may unexpectedly ease the intense nomination pressures on Trans Mountain, potentially averting the severe June apportionments that shippers had anticipated following the pipeline's highly subscribed commercial launch
Weekly Westridge crude oil exports by destination, kbd
Source: Kpler
‘Balanced’ market weighs on Medanito diff, but Cushing draws could offer relief
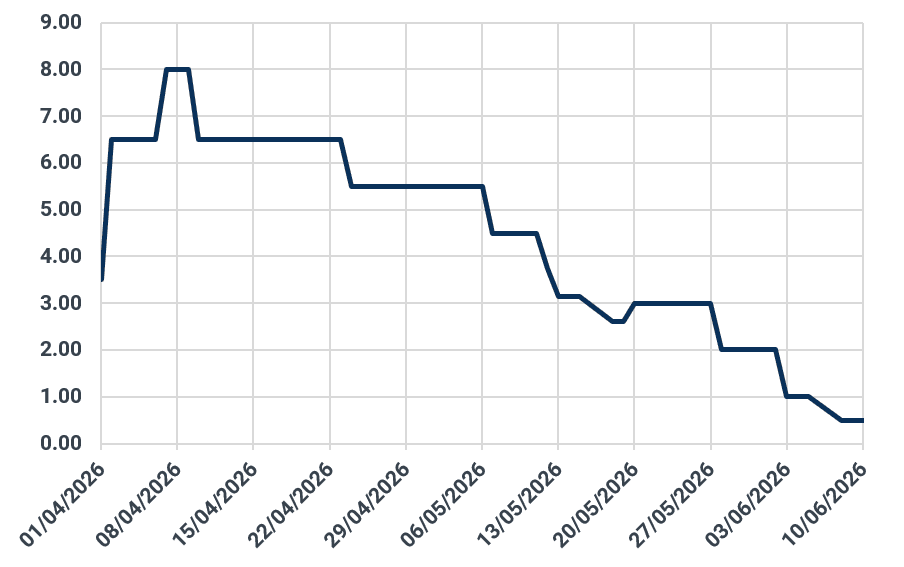
Argentina’s light sweet Medanito crude is facing intense downward pressure, with its premium to ICE Brent falling earlier this week to its narrowest margin since 13 March.
As participants trade the first August-loading cargoes, Medanito's premium has sharply narrowed to just $0.50/bbl against October ICE Brent, from $1/bbl in previous trade (Argus Media). This brings the crude down to pre-war levels on an outright price basis.
This bearish correction is driven by a more balanced spot market, and in Asia, the availability of the UAE's light sour Murban at highly competitive prices is disincentivizing Asian buyers from seeking Atlantic Basin alternatives.
Simultaneously, Medanito faces aggressive competition along the US West Coast, where narrower premiums for the competing Alaska North Slope grade are further suppressing Argentinian values. Consequently, the July trading cycle was extended by two weeks as sellers stubbornly attempted to maintain the record-high premiums captured during June.
Looking ahead however, the low Cushing inventories as we approach peak summer demand is already incentivising more WTI barrels to stay domestically, which could open opportunities for other Atlantic barrels, such as Medanito.
Medanito differential to ICE Brent, $/bbl
Source: Argus Media
Europe and Africa: EU-27 crude inventories are up for a downwards correction
Recovery in Russian refinery runs should weigh on crude exports in June
As previously reported by Kpler, Ukrainian drone strikes on Russian refineries since March have significantly disrupted domestic processing capacity. As these extensive refinery outages curtailed domestic crude demand, Russian crude and condensate exports averaged close to 3.9 Mbd in May, reaching multi-year highs. However, export volumes are likely to ease in June as refinery operations gradually recover. We estimate that Russian crude demand fell from 5.3 Mbd in March to 4.85 Mbd in May, but expect a rebound to around 5 Mbd in June and 5.2 Mbd in July.
Maintenance and repair work is being completed at several major facilities, including the Volgograd, Syzran, Saratov, and Ryazan refineries. As a result, offline refining capacity is expected to decline sharply from roughly 2.9 Mbd in May to just 300 kbd by July (IIR). The recovery in refinery runs is also being supported by seasonal growth in fuel demand and efforts to avoid domestic fuel shortages.
At the same time, we expect Russian crude and condensate production to increase modestly to 10.14 Mbd in June, before rising further to 10.2 Mbd by August. Additional upside may come from the normalization of crude flows through the Druzhba pipeline to Hungary and Slovakia.

See why the most successful traders and shipping experts use Kpler