Weak demand leaves Brazilian November cargoes unsold
Record supply from Brazil and Guyana is meeting softer demand and high freight costs, pushing sellers to cut differentials, with November loading cargoes still remaining unsold.
Key takeaways:
- Latin American differentials stay under pressure. Record Brazilian supply and Guyana’s push to 1 Mbd in December are lengthening Atlantic Basin balances while demand abroad is weak.
- Brazilian cargoes face a slow clearing. A large share of November-loading cargoes is still unsold, and more Middle Eastern crude in Asia is adding competition.
- China stays muted near term. VLCC freight from Brazil to China has eased from about $39/bbl to about $32/bbl, but delivered prices remain elevated and Brazilian offers are moving slowly.
- India is the outlet for Brazilian barrels. Flows are at about 200 kbd in October, a four-month high, and should stay firm in the coming months if Chinese demand stays weak.
- Latin American crude keeps a reliability edge. Its routes avoid Gulf chokepoints, war-risk premiums and STS delays, even though the West-to-East arbitrage limits Asian appetite.
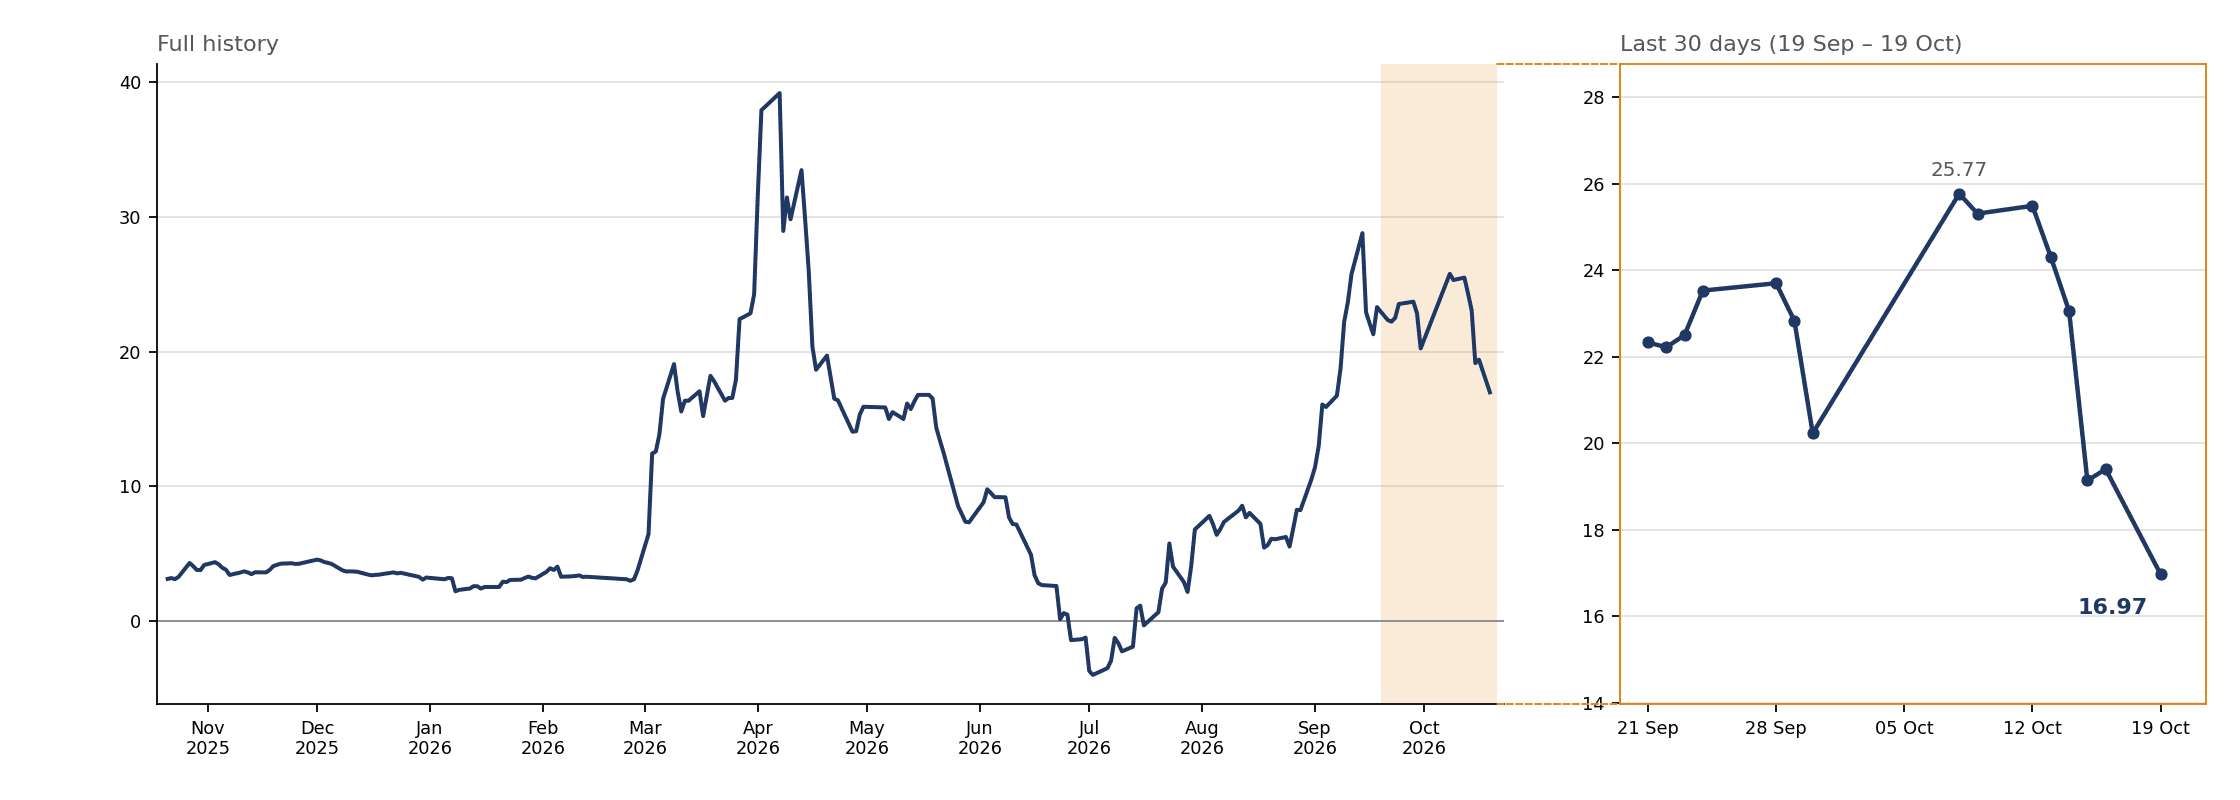
- Demand support is likely in the coming weeks. Lower freight and softer differentials, with Tupi delivered Shandong vs ICE Brent down from about $26/bbl to about $17/bbl, should help Latin American demand.
Record crude supply from Latin American countries such as Brazil, together with expected growth in Guyana, where a new FPSO will lift crude exports to 1 Mbd in December, is lengthening regional balances, whilst meeting weaker demand abroad. Soaring freight costs have also squeezed producers, so regional sellers have had to cut differentials to keep delivered prices lower.
An recent influx of Middle Eastern crude has increased competition in Asia and further dampened demand for Brazilian barrels, and a large share of November-loading cargoes remains unsold.
The cost of shipping a very large crude carrier (VLCC) from Brazil to China fell from about $39/bbl early last week to around $32/bbl (Argus Media). This has kept delivered prices elevated, weighing on Brazilian offers into China and slowing activity more recently.
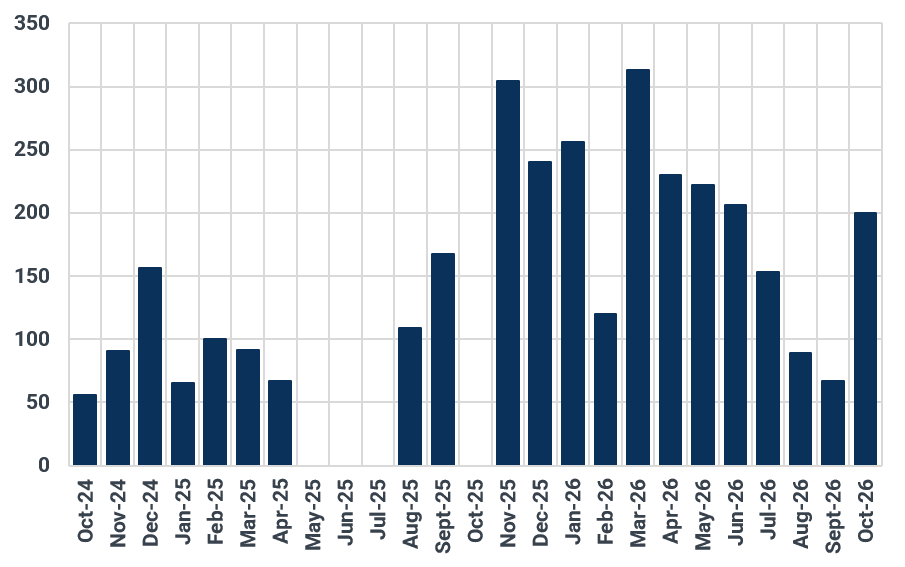
Against this backdrop, higher freight is incentivizing shorter voyages, steering Brazilian sellers toward India, instead of China, with demand from India rising more recently. Flows there have risen to ~200 kbd so far in October (our predictive flow feature indicates a lower overall average for October, but a rise for November), a four-month high, and a trend likely to persist in the months ahead, if Chinese demand stays muted.
Brazil crude exports to India, kbd
Source: Kpler
Whilst unfavorable West-to-East arbitrage opportunities may cap Asian appetite for Latin American grades, these barrels still have a clear advantage over Middle Eastern supply as their routes to Asia avoid the restricted waterways that affect Gulf exports. Moreover, they carry no Persian Gulf war-risk premiums, are not faced with STS transfer delays or demurrage costs.
Tupi delivered ex-ship Shandong vs Ice Brent landed
Source: Argus Media
This, coupled with the recent drop in freight rates and softer differentials could give Latin American demand some welcome support in the coming weeks. Tupi delivered on a ex-ship Shandong basis vs Ice Brent landed has fallen to a multi-week low of around $17/bbl this week (see chart above), down from almost $26/bbl seen at the beginning of the month.

See why the most successful traders and shipping experts use Kpler