
Hormuz: Normalisation no longer needs to wait for a deal
Kpler is moving away from the assumption that reopening the Strait of Hormuz requires a comprehensive political agreement. Our base case will instead reflect slower, uneven normalisation under continued conflict, with shipping recovering through operational adaptation rather than following a single diplomatic trigger. This better reflects what the physical market is already showing. The consensus view had been that a political deal was necessary to reopen the Strait. Instead, rising transits show it is being prized open operationally. Indeed, transits have risen despite persistent hostilities, challenging the previous assumption that sustained attacks would keep traffic close to zero.
Key takeaways
- Kpler is shifting its Strait of Hormuz base case from a deal-led reopening toward slower, managed normalisation. Rising transits show that flows can recover through escorts, ship-to-ship (STS) logistics, operational adaptation, and intermittent diplomatic relief without waiting for a comprehensive US-Iran settlement.
- Diplomacy remains important, but it is no longer the trigger. The consensus view had been that a political deal was necessary to reopen the Strait. Instead, rising transits show it is being prized open operationally, despite continued hostilities.
- US tolerance and mounting Iranian economic pressure support a longer normalisation path. Washington appears willing to sustain economic pressure while facilitating shipping. Deteriorating conditions in Iran increase the incentive for intermittent negotiations and temporary arrangements rather than necessarily producing a comprehensive settlement.
- Crude demonstrates both the potential and the cost of managed normalisation. Middle East crude flows have recovered materially, but continued security risks are keeping freight elevated. A diplomatic solution may not be necessary to restore physical supply, but without one, delivered crude prices are expected to remain high.
- Commodity tolerance remains uneven. Dry bulk is not yet creating sufficient pressure to force political action, while LNG can withstand slower normalization at a cost to European balances. Refined products remain the principal constraint and the market most likely to challenge the new base case.
Market isn’t waiting for diplomacy
Diplomacy is therefore becoming an accelerator rather than a prerequisite. A broad US-Iran agreement remains the cleanest route to durable normalization, particularly if demining and unrestricted use of established shipping lanes are required. Engagement between Gulf states and Iran could provide another route to lower shipping risk. But neither is necessary for incremental volumes to return. Escorted movements, night transits, STS operations, alternative routing, and other operating practices are already creating a third pathway. Short-term diplomatic arrangements could also periodically release pressure without resolving the underlying conflict, making the recovery inherently uneven.
US can wait Iran out
The US tolerance for that status quo has also increased relative to our previous assumptions. Washington can continue applying economic pressure while supporting technical measures that keep some shipping moving. Expectations of a near-term US military escalation have meanwhile receded within the base-case discussion. That combination allows the blockade and higher transit volumes to coexist for longer than initially expected, although the financial and operational cost of maintaining protection remains a risk.
Iranian economics reinforce this direction, but the timing is uncertain. Economic pressure is intensifying as domestic economic conditions will be an increasingly important constraint on Tehran. If the US blockade remains in place, we estimate that Iranian oil revenue will fall to zero by the end of 2026.
However, this does not imply that Iranian capacity or willingness to disrupt shipping disappears quickly. The more credible base-case mechanism is increasing pressure producing periodic negotiations or temporary arrangements that allow additional passage, followed potentially by renewed disruption. Normalisation is consequently likely to be lumpy rather than linear.
Physical market resilience
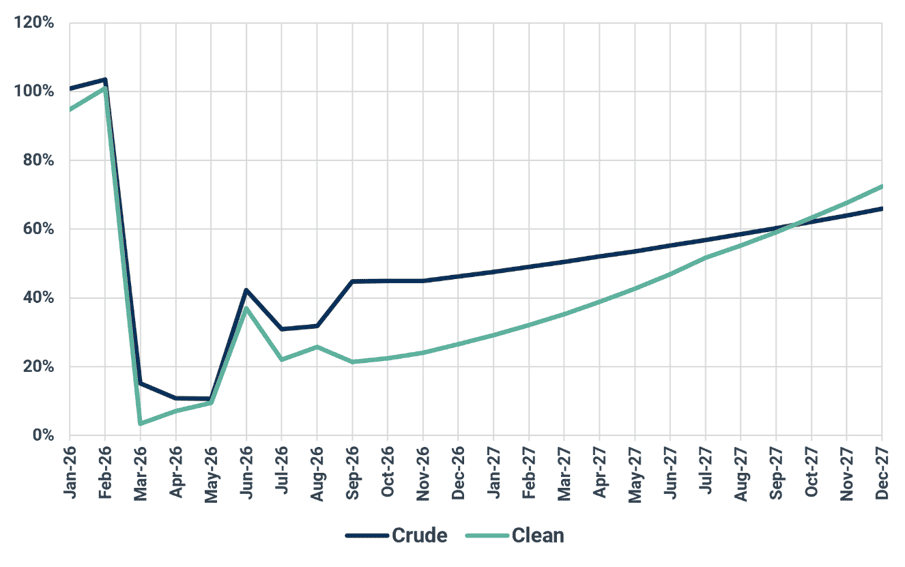
Most importantly, the physical market has demonstrated greater resilience than assumed. Crude is the clearest example. Kpler data shows combined crude volumes exiting the Gulf (excluding Iran) plus volumes from West Coast Saudi and East Coast UAE are around pre-conflict levels of 18.5 Mbd, but when you include diverted volume shipped from the Saudi West coast and UAE East coast its now around 100%. This has reduced the likelihood of a political reopening from crude price pressure.
Middle East* Crude export forecast (Mbd)
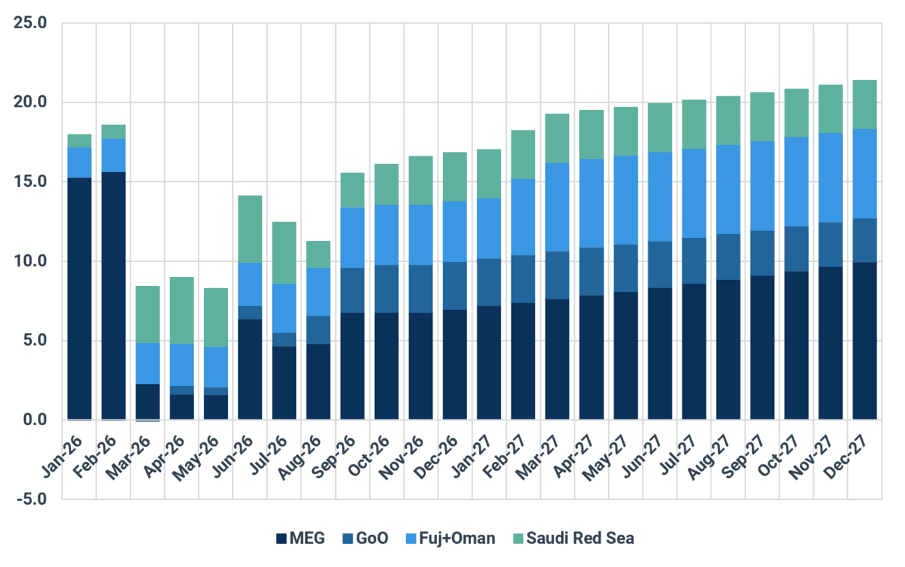
* Middle East Aggregated Exports, Hormuz clearance including GoO + Red Sea , excluding Iranian loadings
That recovery does not mean a return to normal market conditions. While Middle East crude flows have recovered materially, the continued threat to vessels transiting Hormuz is keeping freight costs elevated. The market is therefore demonstrating that a diplomatic solution is not necessary to restore physical supply, but operating without one comes at a cost. Higher freight and risk costs are being embedded into delivered crude economics, meaning buyers can regain access to Middle East barrels without regaining pre-conflict delivered costs. Under our managed-normalisation base case, we therefore expect crude availability to continue improving while delivered prices remain elevated until the security risk to shipping materially recedes.
Refined products are the key pressure point. Middle East Gulf refinery runs and exports have not normalised alongside crude. Clean product loadings from the Mideast Gulf and diverted routes reached 3 Mbd earlier in September before easing to 2.5 Mbd in recent days, an encouraging indicator, but flows remain around 50% below pre-war levels. Sustained product stress remains the most credible commodity constraint on managed normalisation, and present the greatest need for a diplomatic solution.
Middle East* clean product export forecast (Mbd)
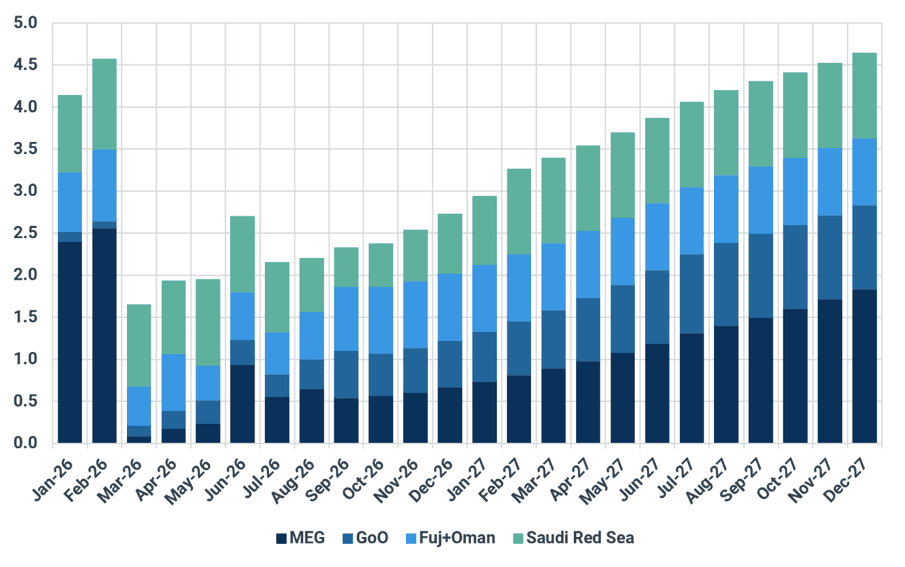
* Middle East Aggregated Exports, Hormuz clearance including GoO + Red Sea , excluding Iranian loadings
Dry bulk is less restrictive. Grain markets are experiencing higher prices, but there is no pressing supply requirement forcing governments to act in the short term. Iran has expanded grain receipts through the Caspian and Chabahar, while imports through Gulf ports continue. Sulphur supply is a more material secondary concern, given the Middle East's importance to global exports and downstream agricultural demand and metal ore processing.
LNG sits between crude and products. Since early September, Qatar has re-commenced shipping cargoes through Hormuz on a dark basis, alongside sustained dark transits from the UAE. LNG exports have witnessed a notable uptick over the past few weeks, but remain below pre-war levels. Prolonged constraints through 2027 would sustain strong inter-basin competition for LNG, keeping prices elevated and making Europe’s summer 2027 restocking cycle more challenging. European underground gas storage inventories are expected to start the winter heating season at around 75% full and are forecast to fall to around 30% by the end of winter. Additional global LNG capacity arrives later in 2027, but project delays mean it cannot fully offset an extended loss of Qatari supply in the near term.
The implication is not that Hormuz has reopened. It is that full reopening should not be expected in the next six months. Our revised base case shows a flatter and extended recovery curve through 2027, reflecting rising but volatile transits rather than a six-month post-deal reopening. The critical stress test is refined products. If constrained Gulf refinery runs push product markets toward unsustainable tightness, the economic pressure for a faster resolution would increase materially.
Crude and Clean Products Strait of Hormuz exports as share of pre-war levels
Source: Kpler

See why the most successful traders and shipping experts use Kpler