As Europe faces a tight Q4, could Spain be overpriced?
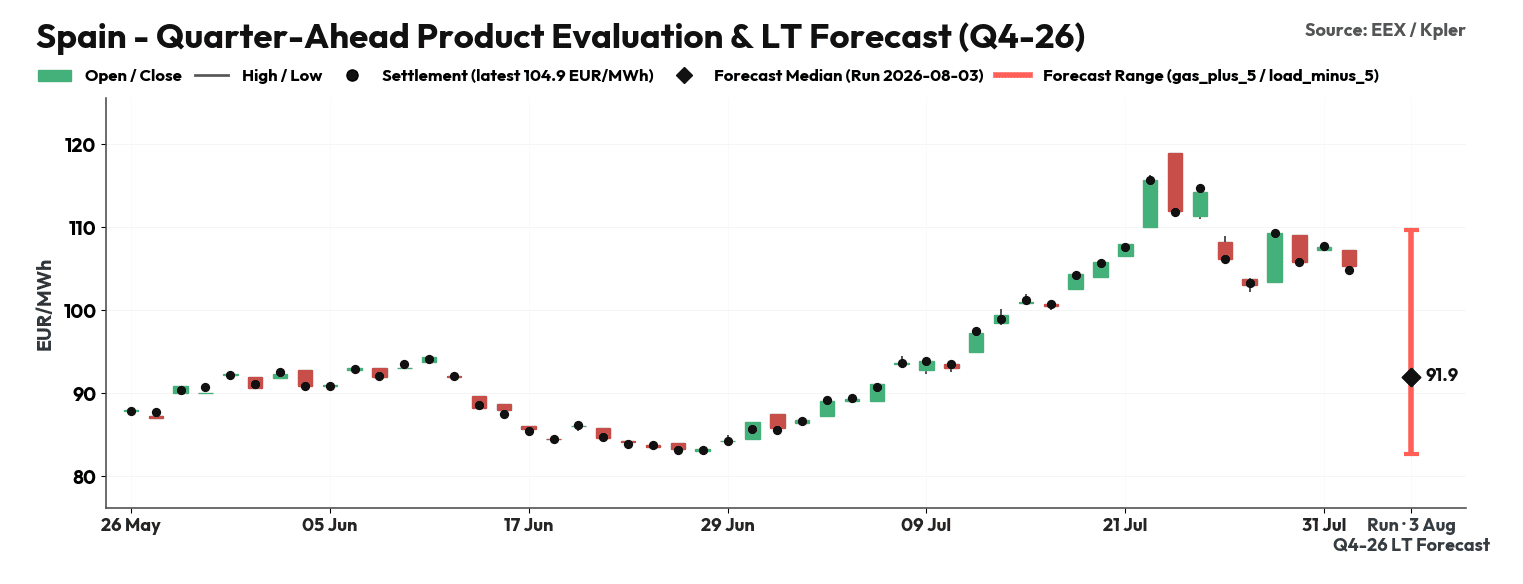
Elevated TTF, low gas storage, and weak hydro have lifted Q4 power prices above the last 3 winters. But Spain's strong hydro position, rapid renewable build-out, and warmer weather outlook leave current market prices of 104.9 €/MWh looking rich, with Kpler pricing 12% below market levels.
Executive Summary
- Europe is heading into a tough winter, with Q4 power prices at 4-year highs. Gas prices (up ~70% y/y) and fragile Alpine hydro are driving CWE Q4 prices up 50 to 80% y/y.
- Spain's Q4-26 forward has rallied 52% y/y, a move Kpler Insight views as unjustified given strong generation fundamentals. Hydro stocks remain ~30% above seasonal norms, nuclear availability looks strong, and solar (+7 GW) and wind (+1.5 GW) additions in 2026 will cap gas's impact on price formation.
- Temperatures are forecast 0.5–2°C above normal across Spain and France during Q4, which should trim winter heating demand and add a further bearish skew to our models.
Market & Trading Calls
ES Q4-26: Bearish. The Kpler median weather year model sees Spanish Q4 power at 91.9 €/MWh, compared with a market price of 104.9 €/MWh (3 Aug), as strong hydro and renewable generation, alongside subdued heating demand, limit gas's impact on prices.
Europe heads into winter at 4-year-high power prices
As of 3 August, Europe faces a tough winter for power prices with 4-year highs across the continent.
With the exception of the Polish Q4 product, up 10% (driven by a broadly stable coal generation stack and a ~1 GW increase in wind installed capacity y/y), most markets are pricing in gains of at least 30% y/y this winter.
In particular, the CWE region and Iberia stand out, with French and German Q4 power products witnessing a recent strong bull rally, up 83% and 50% respectively vs Q4-25.
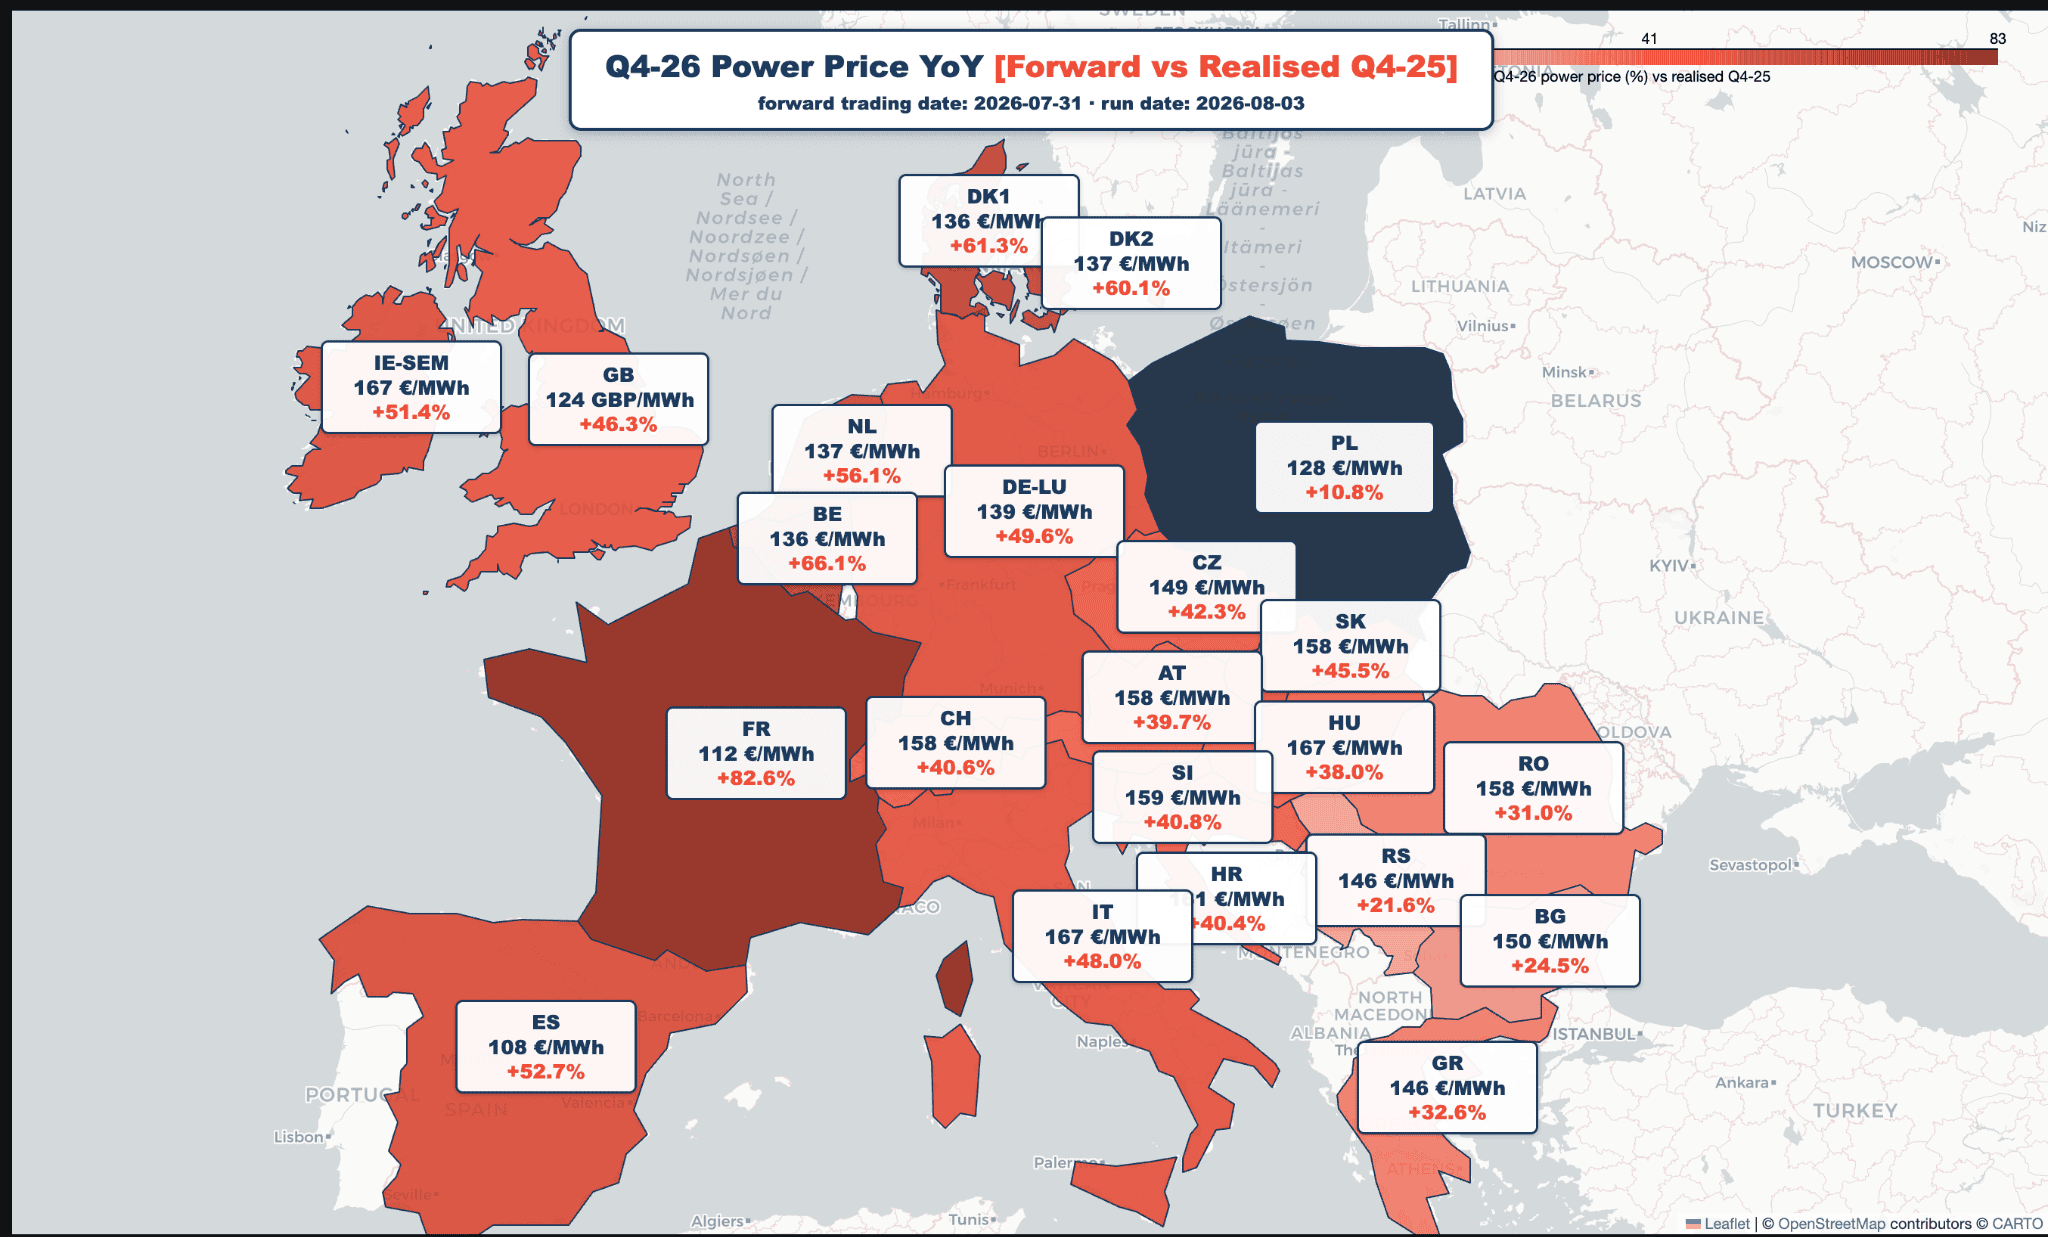
The key driver is gas prices.
Q4 TTF prices currently trade at 57.6 €/MWh, up 70% y/y. The rally reflects geopolitical uncertainty around the re-opening of the Strait of Hormuz, low European gas storage levels (tracking towards 76% by 1 November, according to the Kpler LNG team), and competitive Asian LNG prices. This is dragging continent-wide prices higher as interconnector flows reshape the European merit order.
Several other factors also compound the current market narrative:
- Fragile hydro conditions: particularly in the Alps and southern Nordics (see our latest Kpler hydro outlook).
- Nuclear and thermal risks: additional unplanned maintenance at nuclear and thermal assets, which are operating under significant stress this summer due to heatwaves and drought conditions.
- CO2 prices: EU ETS Dec-26 has rallied, following the EU announcement on 17 July that it would slow the rate of reduction in the emissions cap from 2031 to limit the impact on industry. The market did not experience the anticipated downside for 2026, supporting a medium-term bullish outlook.
However, at Kpler Insight we believe some countries are overpriced.
Looking at Europe as a whole, Q4 appears expensive relative to fundamentals:
- Hydro stocks in Iberia remain abundant despite the start of the wildfire season, while the Northern Nordics basin is well above the past 5-year average.
- The OND (October, November, December) weather outlook points to a mild winter across all Europe and wet in North-West Europe, easing pressure on Southern Nordics hydro stocks and supporting Iberian stocks staying high. The weather outlook is reinforced by the historical track of strong El Niños in Europe, which delivered mild, wet and windy winters.
- Increased renewable additions, coal profitability, and strong French nuclear availability look to temper winter prices.
Overall, while European power prices are deservedly high in certain markets, other pockets of Europe look overpriced according to Kpler Insight.
Spain looks like a key example.
Spain enters Q4-26 with strong hydro reserves, higher nuclear availability and continued renewable growth, supporting a comfortable winter balance. Combined with a mild and wet weather outlook, stable gas prices, and fundamentals, we believe the current Q4-26 market price of 104.9 €/MWh (3 Aug) is overpriced. Using a median weather year, Kpler probabilistic models point lower to 91.9 €/MWh, a 12% discount on current market levels.
Spain’s power mix share can be split into 4 buckets:
- Gas-fired generation (~20%): While it primarily operates as baseload generation, it also provides the flexibility needed to balance the system during periods of market tightness.
- Renewables (~40%): The contribution varies considerably by season. During the summer, solar's contribution is stronger (30% solar and 10% wind). In winter, the balance flips as stronger wind generation becomes the dominant renewable source (30% wind and 10% solar).
- Hydropower (~20%): Run-of-river hydro contributes around 3% of generation in summer, rising to approximately 5% in winter. Pumped-storage and reservoir hydro provide an additional ~15-20%, offering valuable flexibility to the system, particularly during winter.
- Nuclear (~20%): Nuclear generation accounts for the remaining one-fifth of the power mix and operates largely as stable baseload capacity.
At Kpler Insight, our assessment is that risks across all generation technologies remain contained ahead of Spain's winter, making the 52% increase in Spanish Q4-26 vs Q4-25 appear fundamentally unjustified. This is reinforced by the bearish outlook on FR Q4-26 (see our latest Kpler monthly report)

See why the most successful traders and shipping experts use Kpler