
Strategic stock release resets diesel
The announcement that the G7 will release up to 100 million barrels of diesel and crude oil over the next four months in coordination with the IEA has effectively reset gasoil markets, triggering a substantial sell-off in futures markets, and France has already indicated that significant volumes will be made available in the next 20 days. Should that be true, then the tight spot market could ease in a matter of days, lowering physical differentials and values across the board.
Market & trading calls
- Slightly bearish diesel cracks and European and Mediterranean values as the strategic stocks release threatens a sudden supply surge against a still tight backdrop.
- USGC differentials to weaken as export demand and values dip.
- HOGO to strengthen as release affects Europe more substantially given it is a structural short.
G7 member states the UK and France are particularly structurally short on diesel, and France had been proactive in addressing the diesel tightness, delaying implementation of its more stringent winter-specification diesel and floating the idea of relaxing sulfur limits.
France had initially proposed a 50-million-barrel diesel release over four months, which if it were to materialize would be substantial. Total European imports from outside the region were just over 24 million barrels in September. Imports into Europe will of course continue as the global market remains exceptionally tight with outflows of diesel from the Middle East less than half of what they were a year ago and the extension of Russia’s gasoil export ban until the end of October keeping seaborne supply diminished. That said, there is the potential for further downside should Russia return to the market, resuming supply to Brazil and Turkey, and loosening global tightness even further with apparently improved domestic diesel stocks. The advertised strategic barrels may not materialize in full, as some pledged volumes did not after the initial March release, particularly if greater overall supply reaches the market. The political impetus may also wane given US midterm elections take place on November 3.
The release crucially takes the US’ persistent threats to implement a diesel export ban, which would have been catastrophic for prices outside the US, off the table for now. By at least satisfying the US’ demands to release diesel, this ensures that the tap from the USGC, which has been absolutely crucial for global supplies in the wake of the US-Israel/Iran war, remains open. President Trump had been pushing for a diesel export ban as a way to control domestic diesel prices but this was very divisive within the administration. This news has already lowered ICE Gasoil (-5%) and Heating Oil futures (-3%). This stronger HOGO spread will likely persist because, even with more quantities available in Europe, the typical difficulties of supplying PADD 1 remain.
Lower prices do mean that some of the effects of the lower demand in Europe seen this year could be lessened to some degree. However, a lasting fix for the diesel problem – and the high prices - remains greater access to refining capacity and supply principally in the Middle East; structural factors will continue to buoy the market over winter. This release also does not signal optimism that a solution to the Strait of Hormuz crisis is just around the corner.
Europe gasoil/diesel balances (kbd)
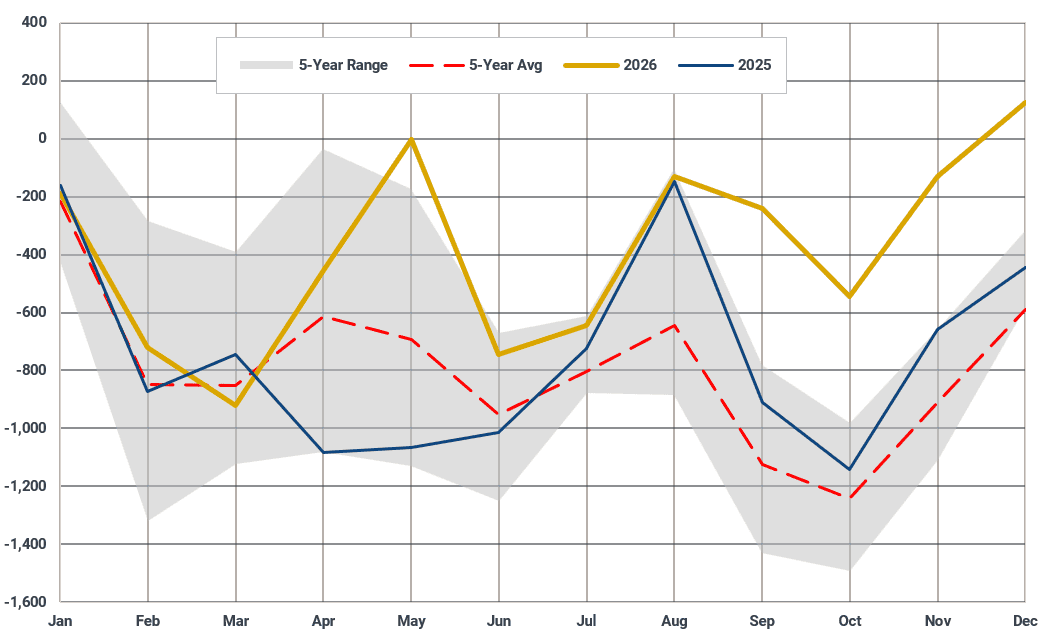
Source: Kpler
Market Insights you can trust
Kpler delivers unbiased, expert-driven intelligence that helps you stay ahead of supply, demand, and market shifts.
Trade smarter. Request access to Kpler today.

See why the most successful traders and shipping experts use Kpler