
US reopening quickly fades as freight climbs
Last week’s reopening of transatlantic arbs from the USGC to Rotterdam was short lived as rising MR freight closed off arbs early last week, with economics deteriorating further by Friday’s close. Rising freight rates East of Suez have also seen distillate arbs out of West Coast India come under pressure.
Trading calls:
- Remain bearish Nov/Dec Ice Gasoil futures: Russian exports have started to pick up, with 173 kbd set to load so far in October, the highest since June, with which should pressure the European complex through displacement into the typical shorts like North Africa, Turkey and Latin America. G7 stock releases will also add pressure.
- Bullish Q4 E/W: Re-tightening of supply out of the Middle East combined with Chinese restocking could see supply tighten East of Suez, while West of Suez will see length added through increased Russian supply.
West of Suez: US windows shut again as freight costs rise
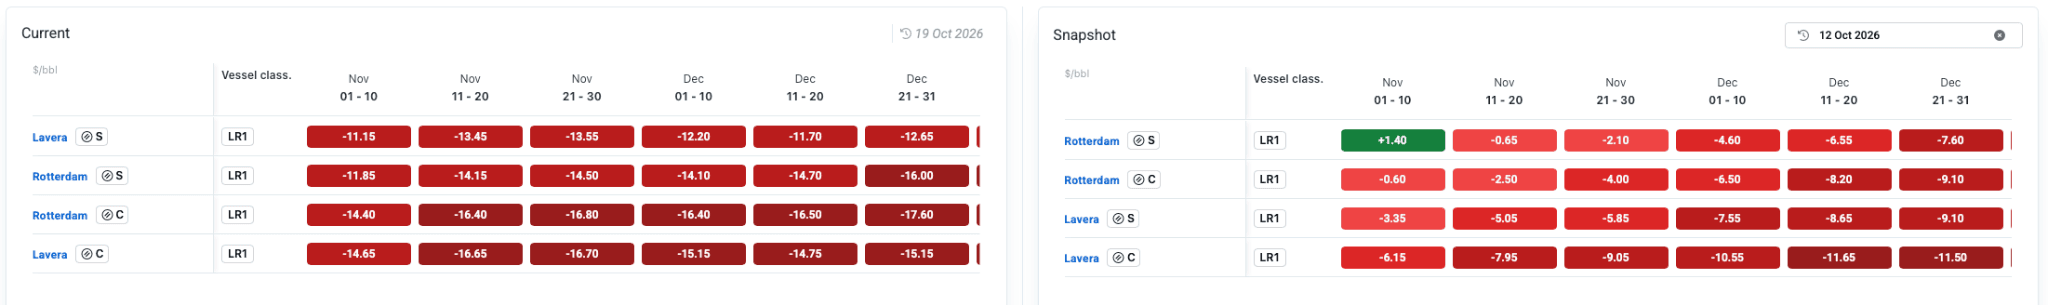
USGC to NWE MR arbs moved briefly into positive territory between 9 and 12 October for mid November delivery, with arb margins rising to around $6.35/t. But margins flipped sharply on 13 October to around -$19.75/t as cash diffs came off with news of French and German stock releases moderately pressuring values in the prompt.
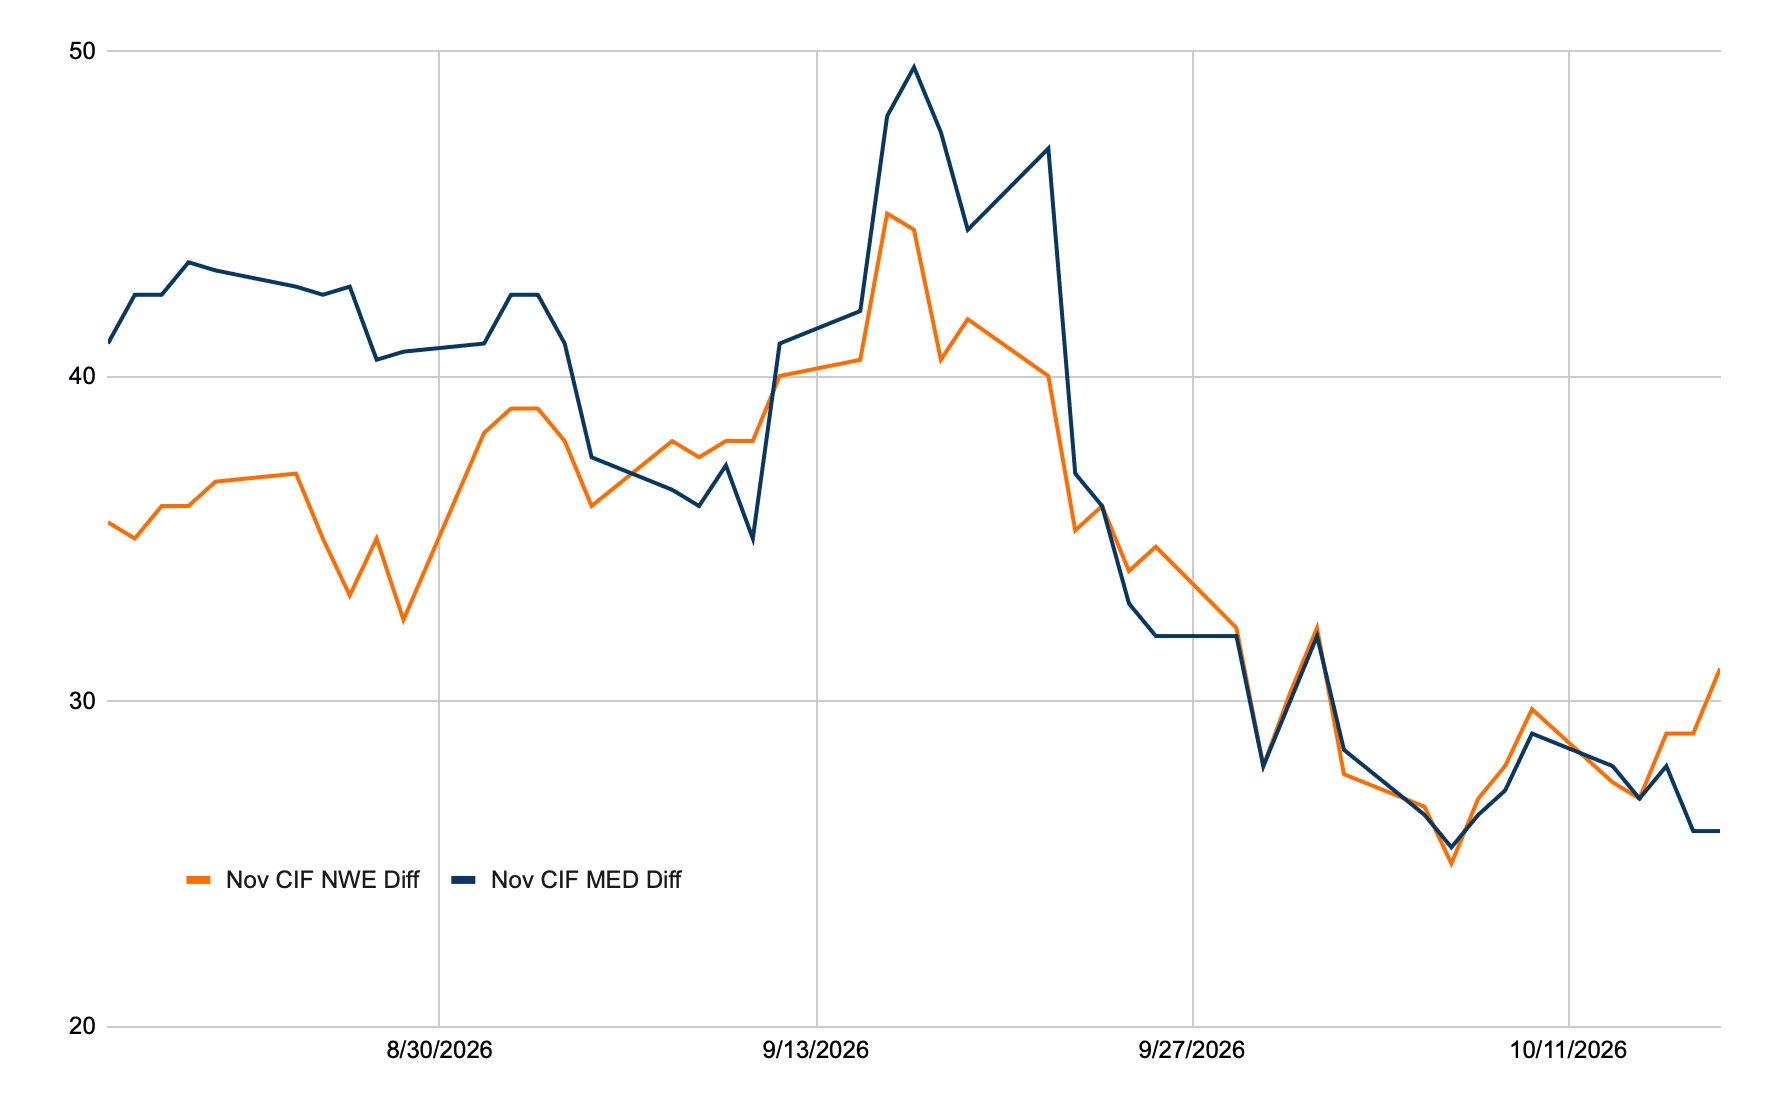
And while 10ppm CIF NWE differentials in NWE crept higher through last week – with November opening this week at +31.50, the highest level since the start of October – rising freight costs have stymied economics this week.
November CIF NWE and CIF MED diffs
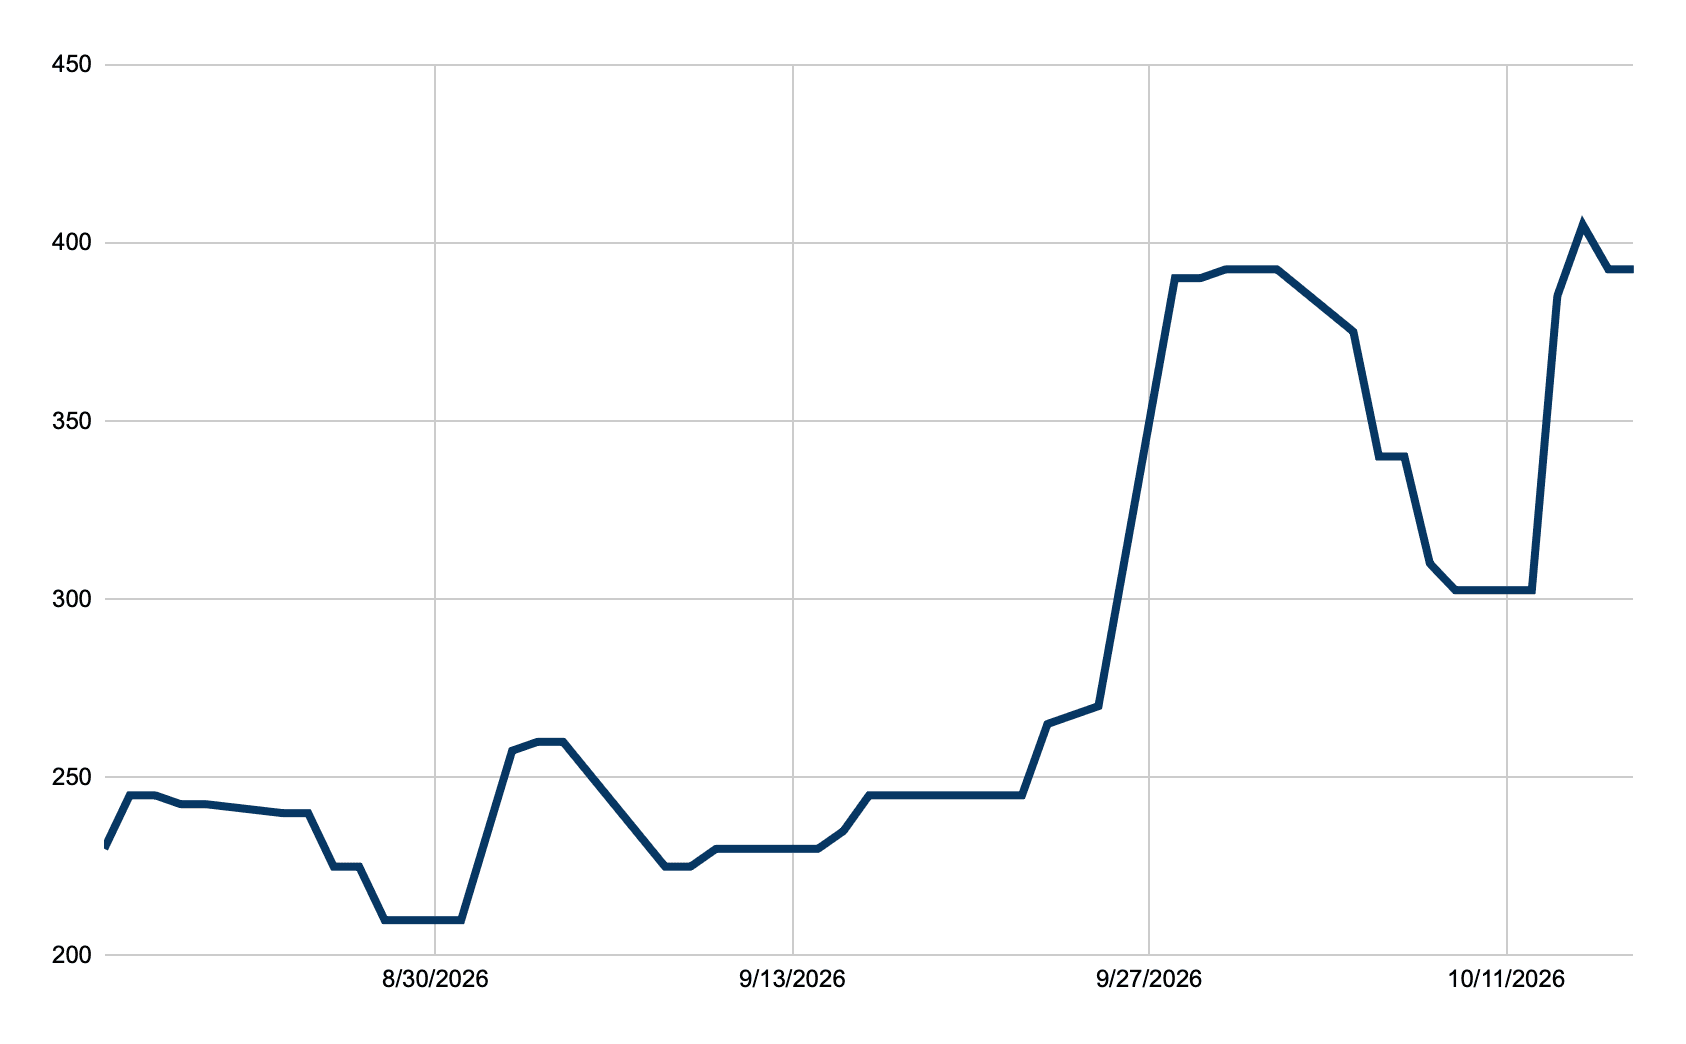
Lower MR rates between 8-12 October – driven by geopolitical news around the US issuing a waiver on Russian diesel exports, – had given support to economics. But MR rates rose by around 29.75% week-on-week, up from 302.5WS to 392.5WS by the close on Friday, closing off arbs into NWE and the Med with the latter also hit by weakening Med differentials.
USGC to UKC MR freight, WS
As a result arbs are closed down the curve into both the European regions across vessel classes. Arb margins for the prompt 21-30 November discharge window in Rotterdam on an MR was marked at -$22.25/t on Monday, with 11-20 December at -$17.50/t, down from +$12.75/t and +10.75/t respectively at the close on Monday 12 October. In the Med margins for 21-30 November were also down at -$39.25/t from -$3.50/t and mid-December similarly weaker at -$32/t, off from -$6.25/t a week prior.
Diesel availability is set to increase in the coming weeks as G7 stock releases come to fruition. Russian flows will also add length to the Atlantic basin as mentioned last week. Kpler expects these barrels to land in North Africa, Turkey, WAF and Latin America primarily removing competition for the USGC barrels that NWE and the Med typically rely on.
US diesel exports have been high recently, though down from the summer peak, at 1,230 kbd so far in October with the 66% signalling for Latin America where strong agricultural demand continues to support export flows.
More supply in the major shorts in the coming weeks - directly or indirectly - should allow the US to build its buffers again, particularly on the East coast where 0-15 ppm sulfur stock level are hovering around 7.4mn barrels below 5 year average levels, according to EIA data.
Arbs into Europe and the wider Atlantic basin are likely to remain closed in the coming sessions, especially in the prompt. In the medium term however we could see some strength as restocking – following the G7 release – will inevitably need to occur.
Executive summary
Diesel arbitrage margins (19 October 14:30 UTC, change vs 12 October 18:30 UTC)
East of Suez: freight shuts India out of the Med
Jamnagar to Europe arb margins, w/w
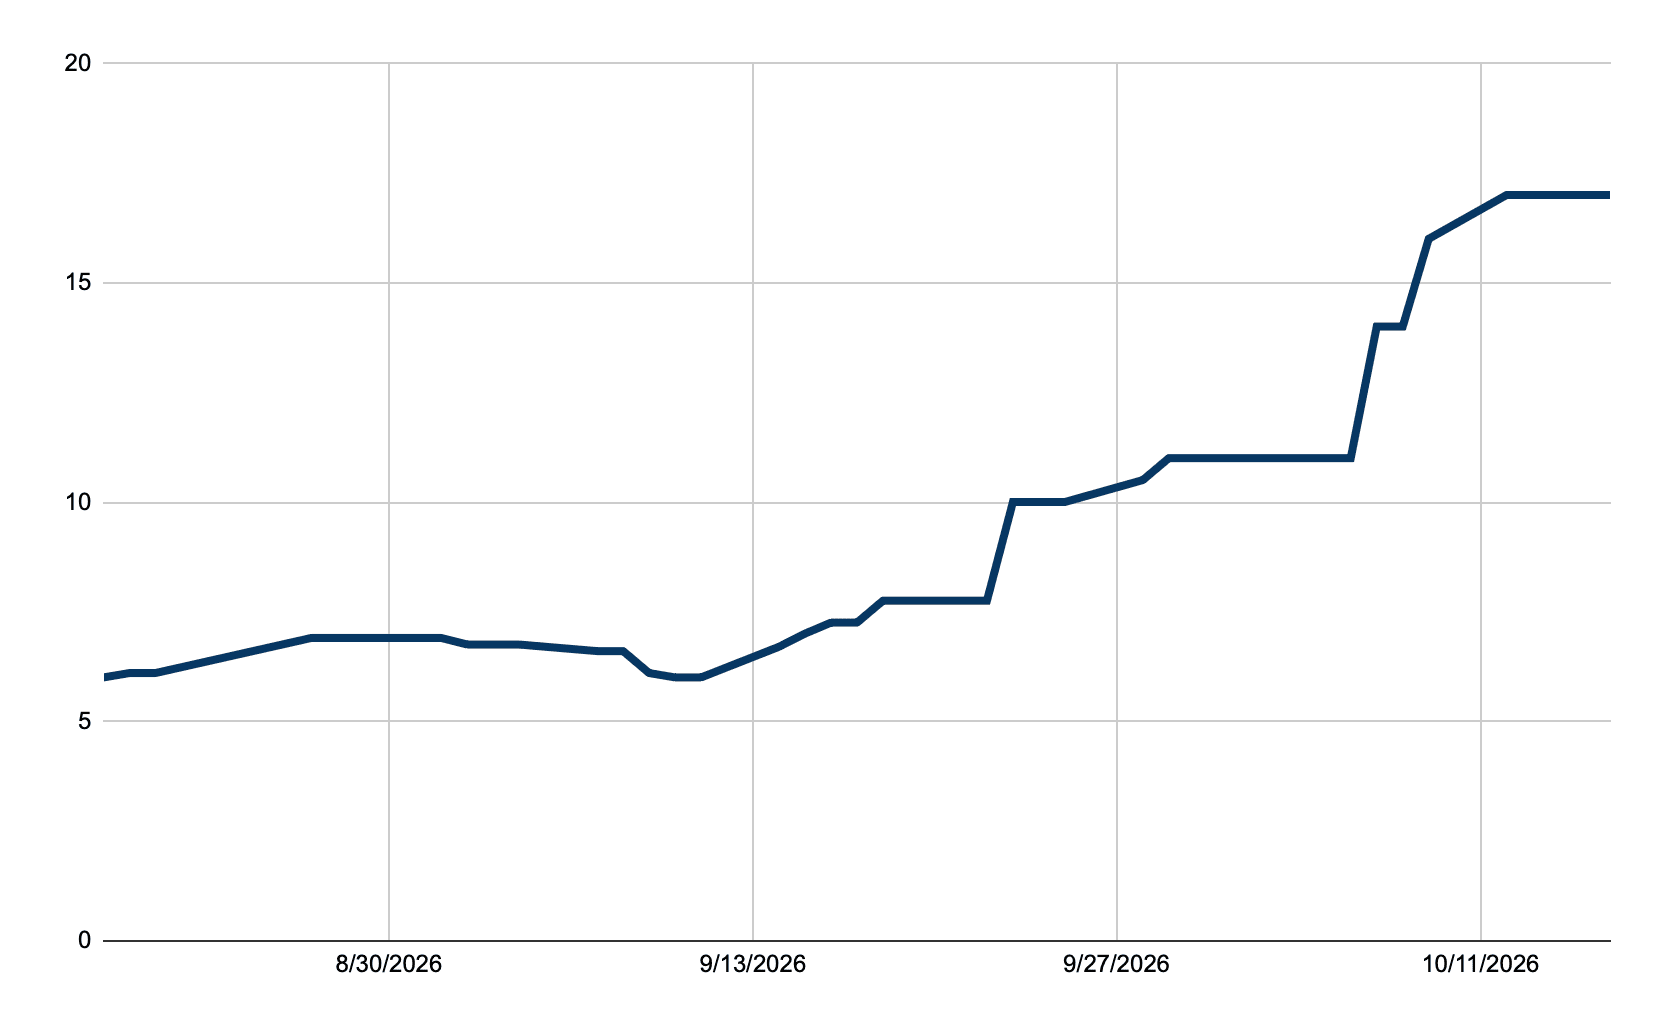
Arbs out of WCI into Europe deteriorated further – with margins for LR2s landing in the Med and NWE via Suez for 21-30 delivery both declining by around $65.50-66/t week-on-week – driven once again by higher and higher transportation costs. LR2 rates on the lane have risen to around $212.50/t, up 6.25% from the start of the month.
LR2 WCI to UKC, $mn
Regional arbs have also deteriorated. WCI to Singapore MRs came off by around $6-8/bbl across November to January loading windows.
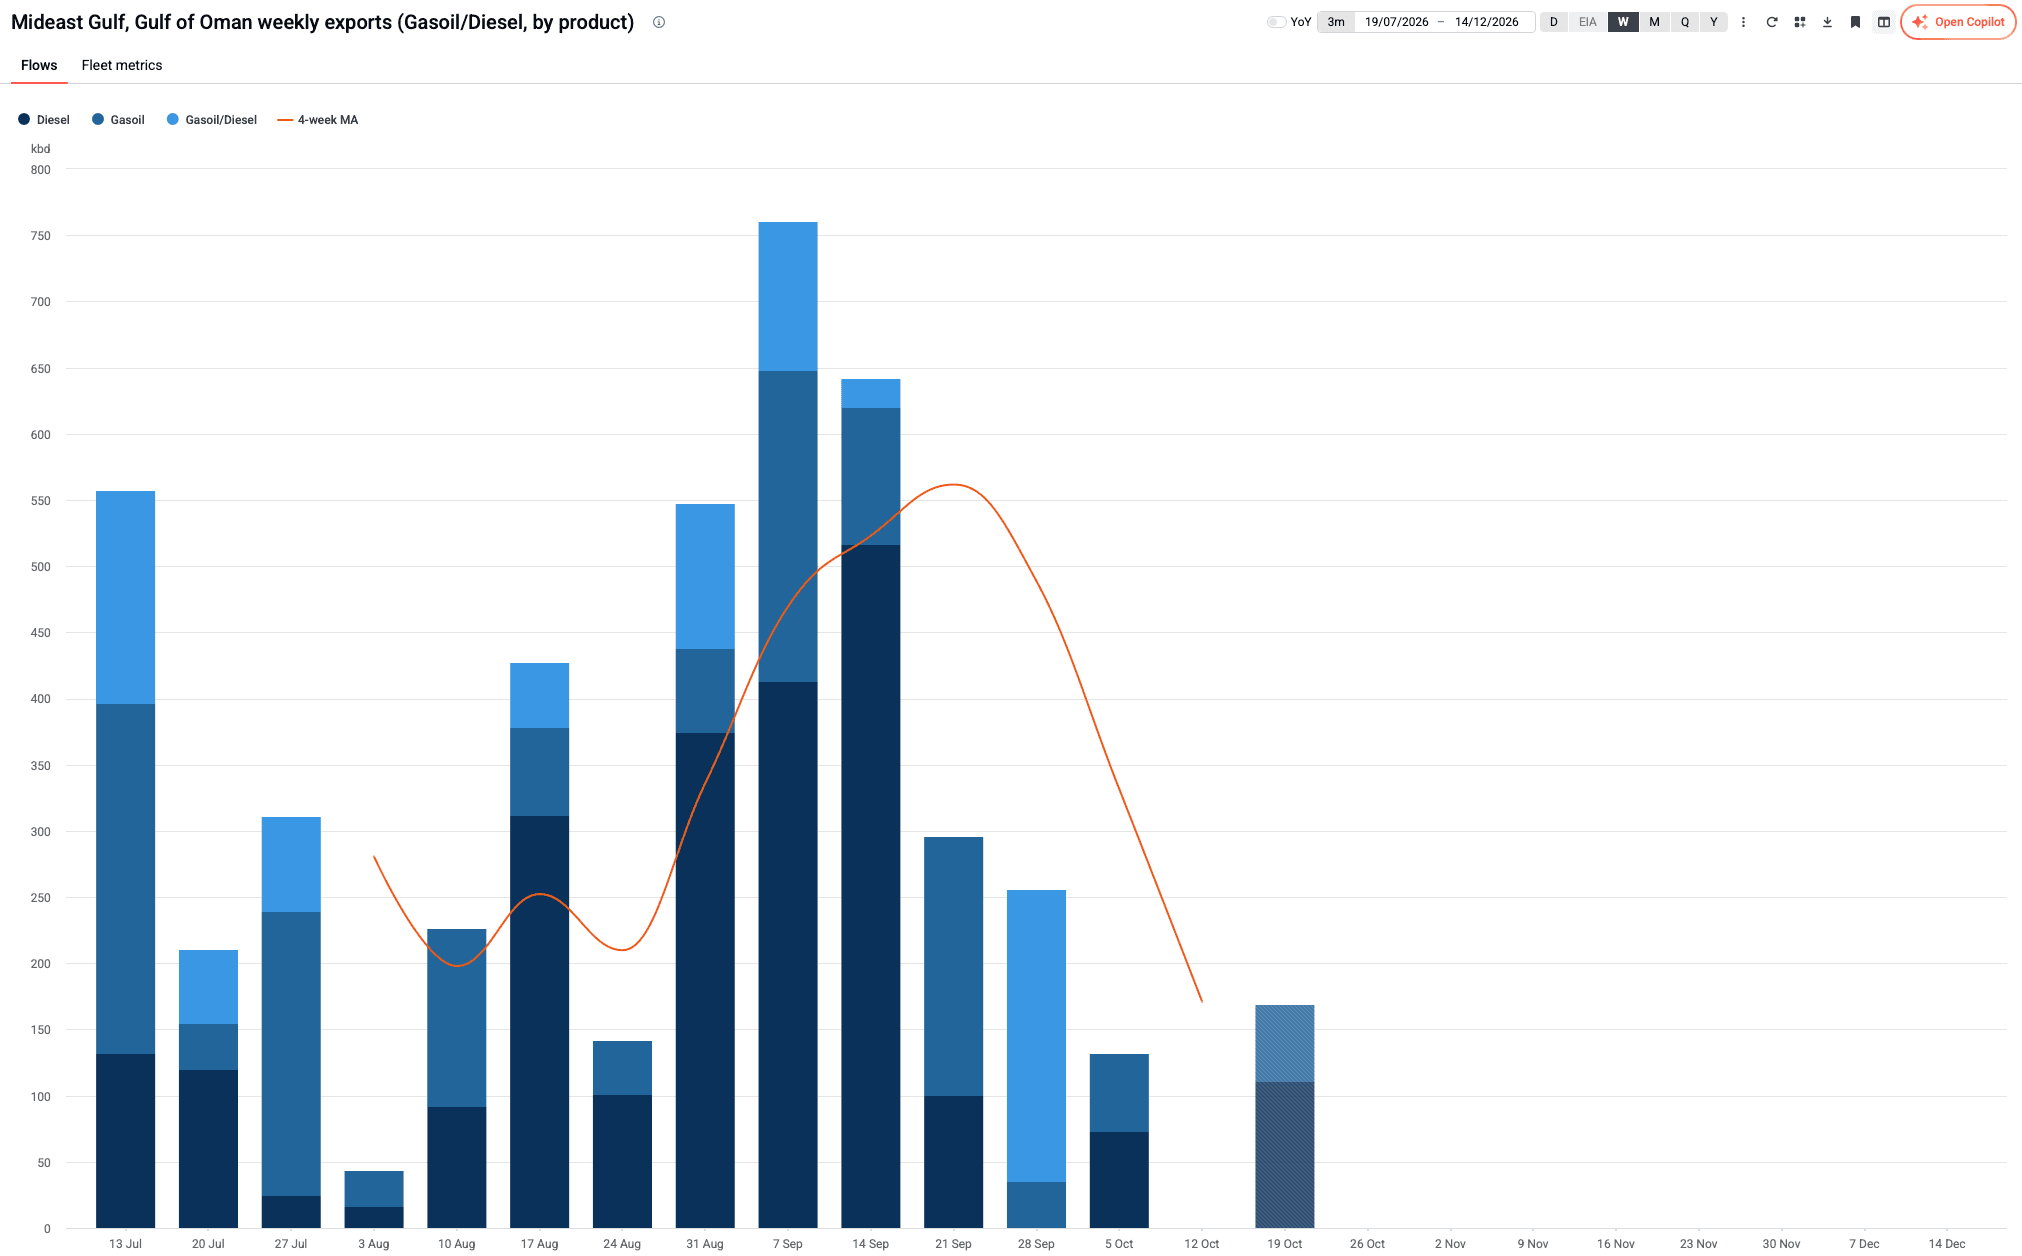
While arbs are closed, focus will return to supply in Southeast Asia in the near-term. While the region was mostly well-supplied last month with exports from China tracking above the 5 year seasonal average in September at 116kbd, exports to the region are lagging so far in October. Despite China’s gasol/diesel output expected to rise in Q4, higher exports are likely to be limited due to domestic restocking requirements. Attacks in the Strait of Hormuz have also intensified in recent days, limiting the flows of gasoil/diesel out of the region so far in October, with none leaving the Mideast Gulf last week. These supply constraints could see the East of Suez market tighten in the coming weeks, narrowing E/W spreads.
Unmatched middle distillate arbitrage intelligence
Evaluate global physical trading opportunities with complete transparency. Pricing, freight, fixtures, and flow data in one decision-ready platform.

See why the most successful traders and shipping experts use Kpler
Pricing, freight, fixtures, and flow data in one decision-ready platform.