Gasoline and diesel inventories stage a temporary recovery
The latest EIA data release for the week ending September 4 showed that crude inventories continued to decline w/w as refinery crude intake and utilization remained elevated. Against a backdrop of tight balances and high crude oil prices, US diesel prices reached a historical high, while retail gasoline prices remained at multi-year seasonal highs.
Market and trading calls:
- US commercial crude inventories fell by 391kb w/w, following the previous week’s 4.5Mbbls draw, while refinery gross inputs and utilization rates remained largely unchanged from the previous week’s highs.
- Total product inventories rose by 6.7Mbbls w/w, largely driven by builds in gasoline, diesel, and propane and propylene.
- US domestic fuel prices remain elevated, with diesel retail prices reaching a historical high of $5.97/gal on Labor Day.
After falling by 4.5Mbbbls in the previous week, nationwide commercial crude stocks continued to decline, falling by 391kb w/w to 424.1Mbbls, broadly in line with the year-ago level and the 5-year average. Gross refinery inputs saw only a negligible w/w change (-32kbd), remaining at around 17.6Mbd level, while refinery utilization rates decreased by 0.2pp w/w to around 97.8%, still the highest seasonal level in the past five years.
Total product inventories increased by 6.7Mbbls w/w, driven by builds of 1.3Mbbls in gasoline, 2.1Mbbls in diesel, 159kb in Jet fuel, and 3.1Mbbls in propane and propylene. Fuel oil stocks fell by 795kb after rising by 2.1Mbbls over the previous two weeks. Gasoline and diesel inventories remain well below their 5-year ranges, and the weekly builds reflected lower gasoline demand (-371kbd w/w) and diesel exports (-179kbd w/w).
Low inventories, alongside rising crude oil prices, have continued to push fuel prices higher. Weekly average regular conventional retail gasoline prices increased by $0.08/gal w/w and $0.13/gal m/m to $4.00/gal, the highest seasonal level in at least the past five years. Average retail diesel prices rose by $0.37/gal w/w and $0.71/gal m/m to $5.97/gal, the highest number in EIA’s record.
US: Weekly nationwide crude stocks (excluding SPR) (Mbbls)
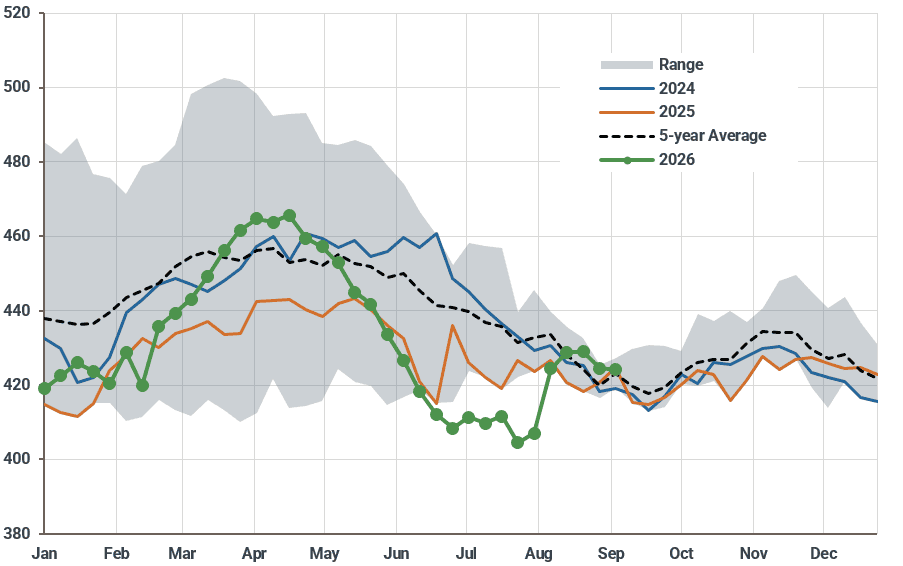
Source: EIA
US: Weekly refinery utilization (% vol)
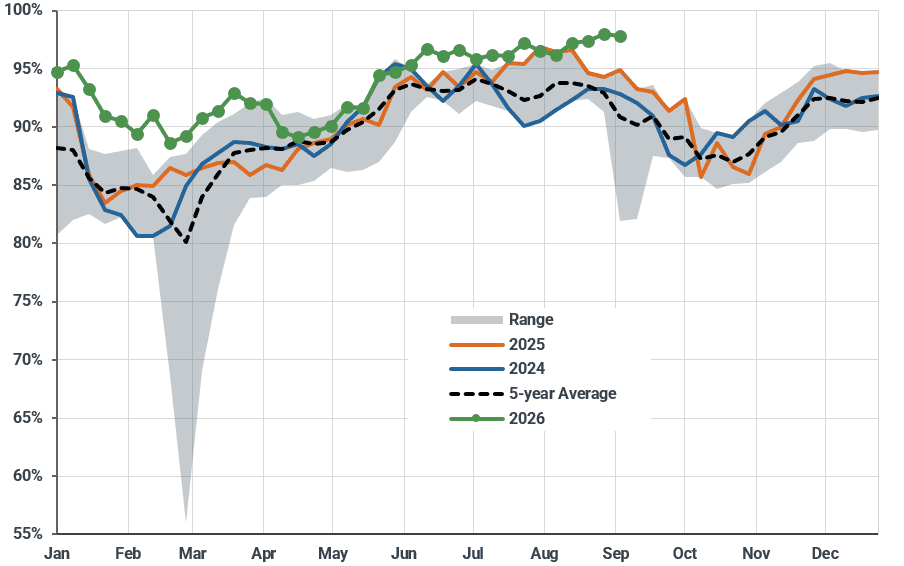
Source: EIA
US: Weekly No 2 diesel retail prices ($/USG)
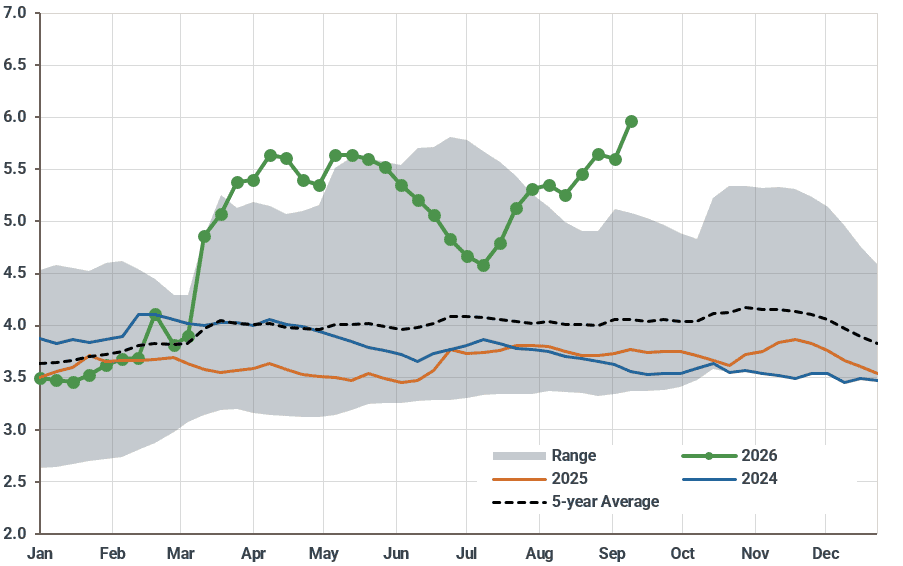
Source: EIA
Market Insights you can trust
Kpler delivers unbiased, expert-driven intelligence that helps you stay ahead of supply, demand, and market shifts.
Trade smarter. Request access to Kpler today.

See why the most successful traders and shipping experts use Kpler