Seven months on: 2 bn bbl lost, 5 Mbd still offline, and no deal in sight
As the war enters its eighth month, 2 bn bbl have been lost and 5 Mbd remain offline, leaving global buffers thin and Western inventories running low.
Key Takeaways
- Cumulative outages: Cumulative Middle East crude and condensate production outages surpassed 2 bn bbl this week.
- Current total outages: As of 6 October, roughly 5 Mbd of Middle Eastern crude and condensate production remains offline versus February 2026 levels, with a large share coming from Iran.
- Exports: Total Middle East crude and condensate exports have temporarily returned to pre-war levels in recent weeks, helped by UAE output above its pre-war level and a likely temporary Saudi crude supply ramp-up to near its 12 Mbd capacity at the end of last month.
- Saudi outlook: East-West pipeline flows have recovered to 5.8 Mbd, but the threat of further attacks clouds the outlook, keeping our expectations for Saudi crude supply ~9 Mbd this month.
- Houthi risk: Houthi strikes recently damaged the Jazan and Najran airports, and the group has warned that Saudi oil facilities and the Bab al-Mandeb strait could be targeted.
- Saudi storage: Saudi Arabia strongly built up underground storage in August (using a balancing factor surplus of 1.7 Mbd). Drawdowns began in September and continued into early October, supporting flows out of the country.
- Saudi September balancing factor: The slight ~150 kbd surplus seen in September turns negative once ~450 kbd of dark Red Sea loadings are included, which indicates some underground storage unwinding last month. Saudi's balancing factor turns even more negative when including potential exports out of the Gulf of Oman, partly offsetting the elevated balancing factor in August.
The war continues unabated and shows no signs of slowing. With tensions between Saudi Arabia and the Houthis in Yemen escalating in recent weeks, Middle East crude and condensate outages continue to reshape global crude markets.
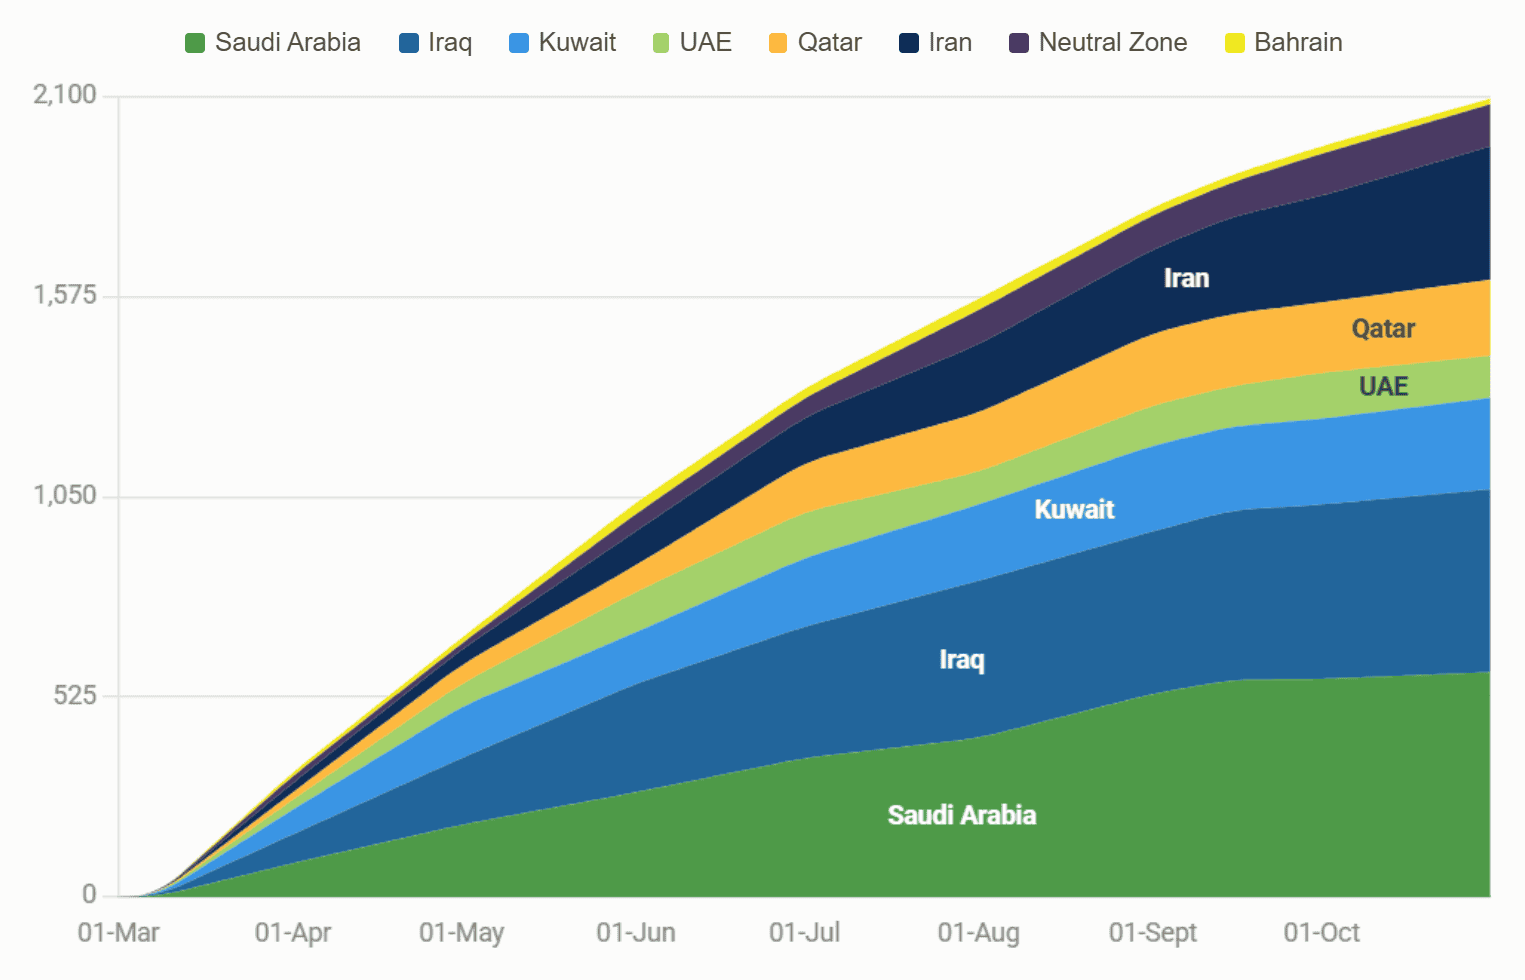
Cumulative Middle East crude and condensate production outages surpassed 2 bn bbl this week (see chart below).
Cumulative crude and condensate supply outages, Mbd
Source: Kpler
Total Middle East crude and condensate exports have temporarily returned to pre-war levels. Drivers of this are UAE production running above its pre-war level and a recent, likely brief, rise in Saudi crude output to close to its 12 Mbd capacity at the end of last month, according to market sources.
This assumption is corroborated by rapidly rising Saudi crude and condensate exports, with loadings averaging 9.1 Mbd in the week beginning 21 September, a post-COVID high.
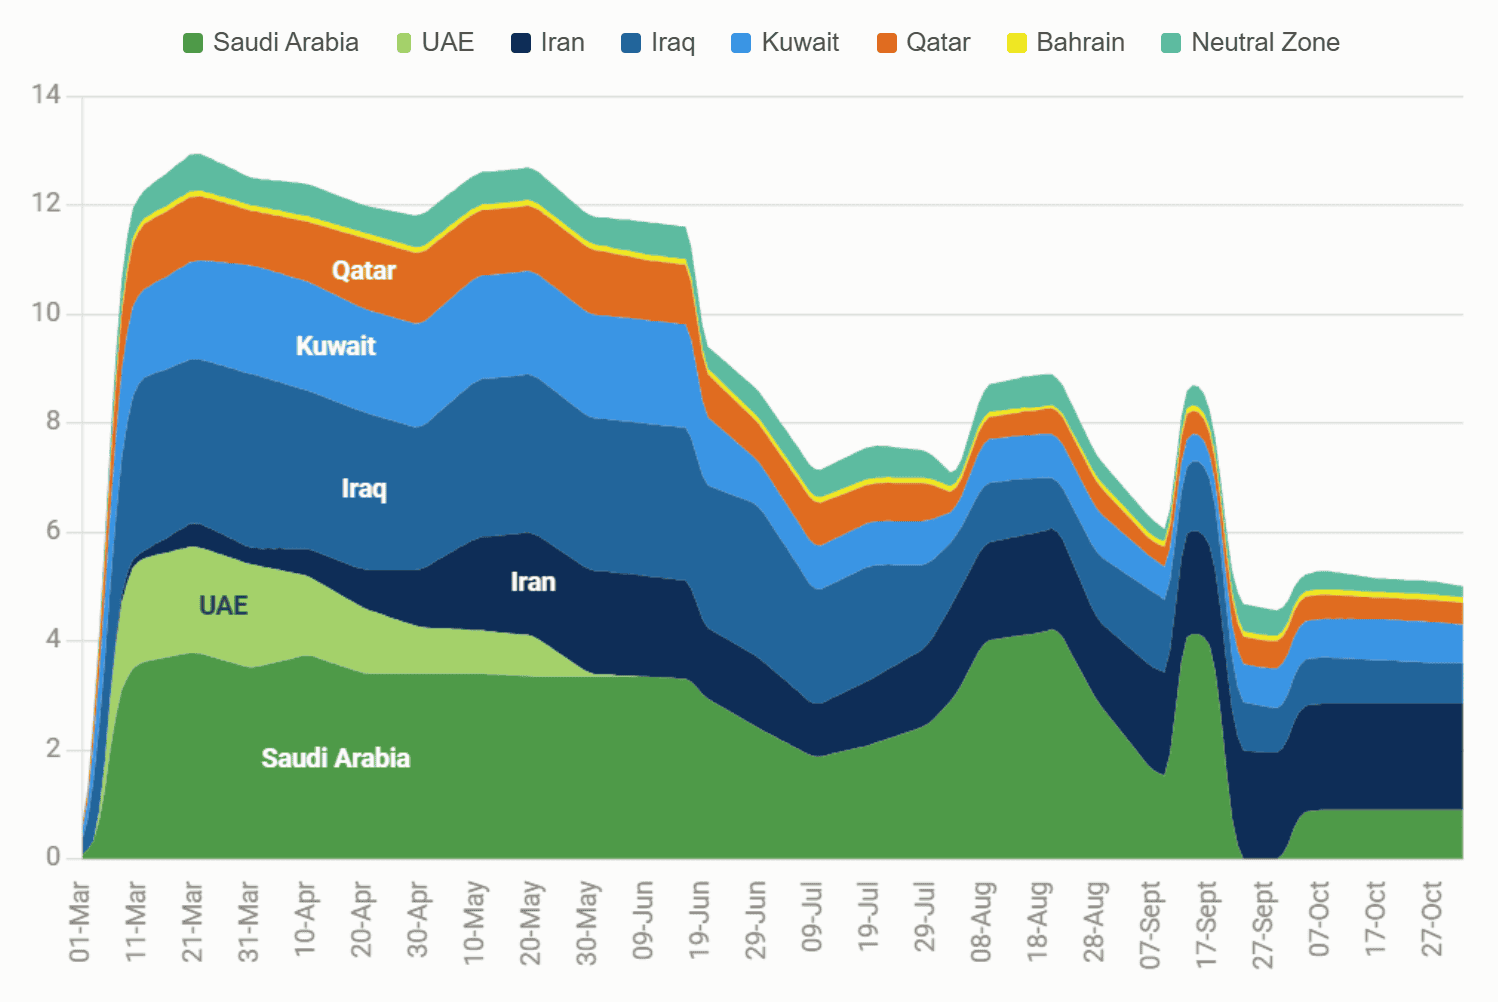
Middle Eastern crude and condensate supply outages, Mbd
Source: Kpler
Nevertheless, this ramp-up likely was short-lived. Given this, we estimate that roughly 5 Mbd of Middle Eastern crude and condensate production remains offline (as of 6 October), compared to February 2026 levels.
A large portion of the ongoing supply outages continue to stem from Iran, which is currently producing at levels that largely reflect domestic demand, with onshore crude inventories only having limited amounts of additional spare capacity remaining.

See why the most successful traders and shipping experts use Kpler