
Aframax rally forces MRs into European dirty trades
MR dirty-ups have accelerated through the second half of 2026, with around 250 vessels now trading in the dirty pool, equivalent to 12% of the fleet. Uncompetitive larger-vessel rates have created opportunities for MR tonnage, tightening Atlantic clean availability by around 92 vessels since August. However, narrowing dirty trading incentives could encourage a gradual return to clean employment, easing supply constraints.
Key Takeaways
- MR dirty-ups have accelerated, with around 250 vessels now trading in the dirty pool, equivalent to 12% of the fleet, a level last seen in 2017.
- Uncompetitive larger-asset rates, particularly across Aframaxes, opened short-haul opportunities for MR tonnage in the European neighbourhood, encouraging cargo downsizing and supporting the class’s utilisation across regional short-hauls.
- Rising MR dirty-ups, topped up with West-to-East repositioning have withdrawn around 92 vessels from Atlantic clean employment since August, tightening tonnage availability and supporting clean Atlantic MR rates.
- Narrowing dirty trading incentives, as mid-size rates in the Atlantic retreat and clean MR rates hold firm on tighter supply could prompt a slow-down in vessels opting for dirty employment.
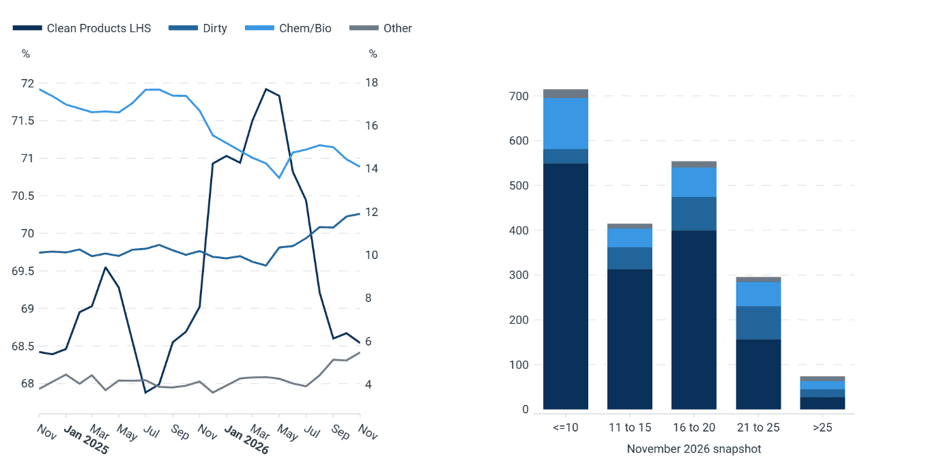
While clean-to-dirty switching has been a recurring theme in the LR2 market since the outbreak of the US-Iran war, dirty-ups have become increasingly common in the MR segment as well, with the trend accelerating thus far in the second half of the year. As of early November, approximately 250 MRs, representing around 12% of the total fleet, trade in the dirty pool, a level last seen in 2017. Most of these conversions have involved older tonnage, with vessels aged 15+ accounting for roughly two-thirds of the dirtied-up fleet.
MR employment by age product type and age bracket
Source: Kpler
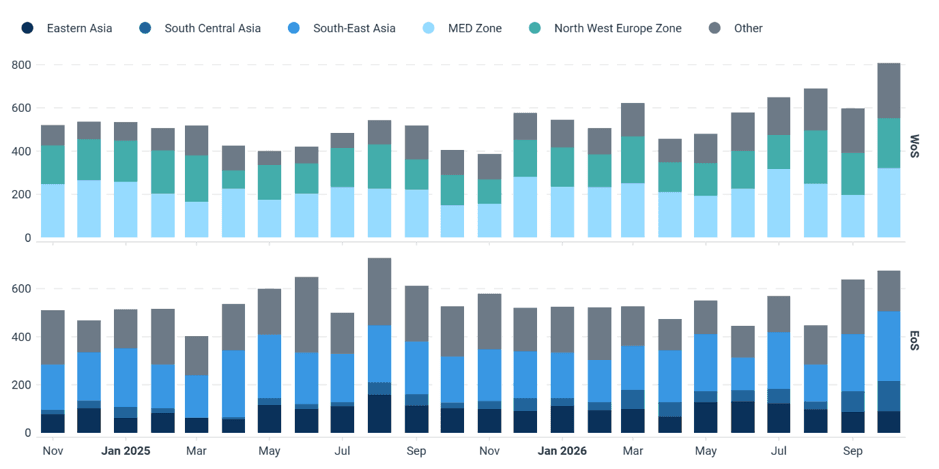
MR dirty trade volumes reached a new high of 1.48 Mbd in October 2026, with momentum building further during the first week of November. Gains were led by the West of Suez (WoS) market, where loadings climbed to approximately 0.8 Mbd, driven by increased activity in Northwest Europe (NWE) and the Mediterranean (MED). Meanwhile, East of Suez (EoS) volumes rose to around 0.6 Mbd, with gains primarily concentrated in South-East and South-Central Asia.
MR dirty trades by origin trading region (kbd)
Source: Kpler
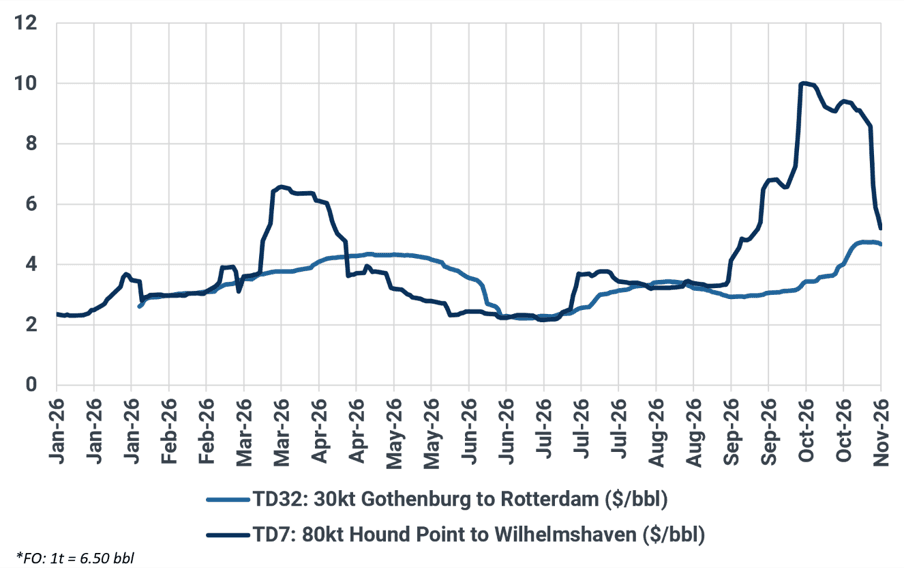
Looking more closely at the key WoS growth regions, a breakdown of the products carried helps shed light on the incentives underpinning these dirty-up trends. In NWE, support for MR utilisation has come primarily from the dirty product segment. Although total NWE DPP loadings declined in October, MR utilisation benefited from larger vessels, mainly Aframaxes and Suezmaxes, accounting for a smaller share of regional exports. Basis a DPP cargo, cross-UKC Aframax rates (TD7) averaged $9.02/bbl in October, up from $4.80/bbl a month earlier, as the cancellation of Yanbu barrels triggered a scramble for replacement short-haul supplies from Europe. The Cross-UKC MR benchmark averaged $3.76/bbl over the same period. This sharp increase in the spread pushed larger vessels away from shorter-haul DPP employment, creating opportunities for MR tonnage.
TD32 vs TD7 $/bbl cost FO basis
Source: Baltic Exchange, Kpler
In the MED, however, the additional support for MR utilisation appears to have come primarily from crude rather than dirty product trades. These flows have increasingly supported regional MR employment. In July, activity was driven by Algerian short-haul exports to Europe, while by October the focus had shifted towards regional Kirkuk trades out of Turkey. This coincided with the spillover of the Atlantic Aframax rally into cross-MED rates, which climbed to $14.22/bbl.
MR dirty trades by origin trading region and product (kbd)
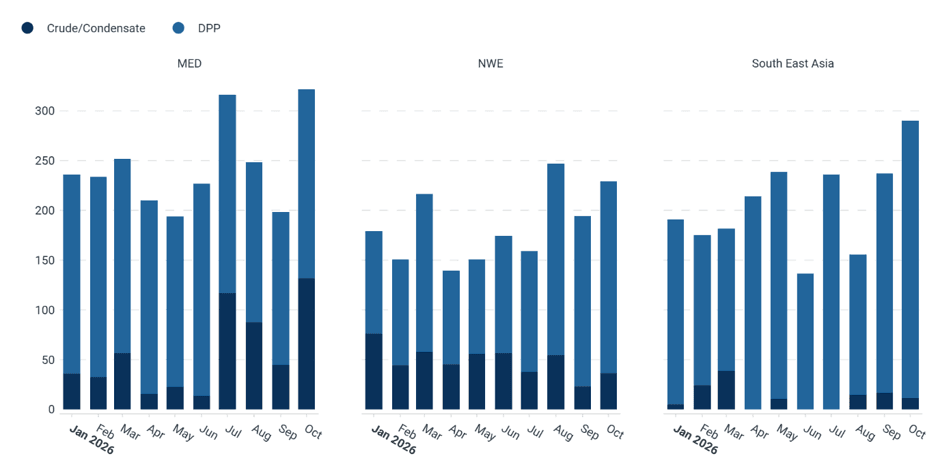
Source: Kpler
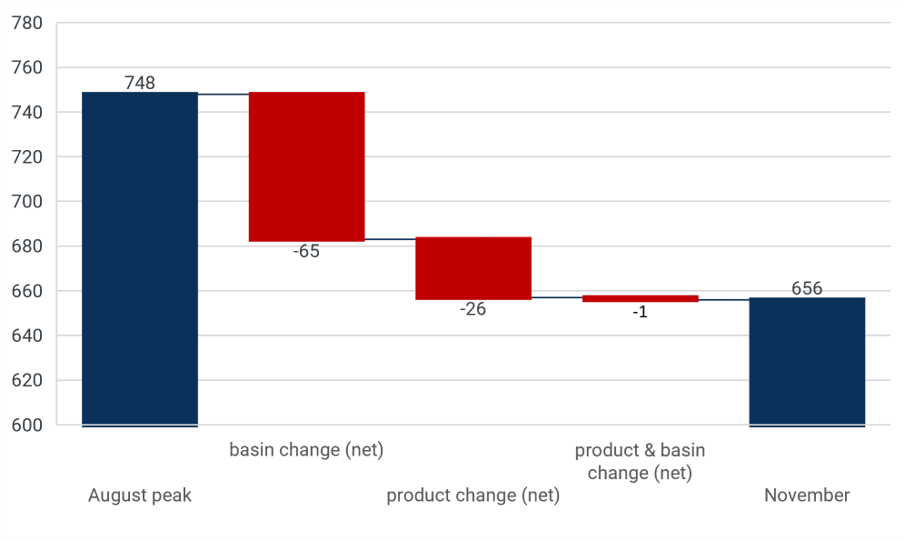
he ramp-up in MR dirty-ups has, in turn, provided some supply-side support to Atlantic MR clean rates. This has been further reinforced by uncompetitive LR2 rates downsizing some West-to-East CPP flows towards MRs, prompting tonnage to reposition in the EoS. Overall, clean MR employment in the Atlantic basin has fallen by approximately 12%, or around 92 vessels, from its August peak.
Change in Clean MR employment in the WoS
Source: Kpler
Looking ahead, while November could see some residual momentum in MR dirty trades, the financial incentive to switch has narrowed.Atlantic mid-size rates have cooled considerably from October's highs, with both cross-UKC and cross-MED Aframax rates now assessed at around $5.00/bbl. Although upside remains possible, a return to October's highs appears unlikely. This should allow larger vessels to reclaim market share in both NWE DPP and MED Crude/Co trades. At the same time, clean MR rates in the Atlantic basin remain supported by tighter tonnage availability and a strong US Gulf market, although they remain susceptible to a downward correction. Indeed, cross-Continent clean earnings (TC23) have now reached parity with their dirty counterparts (TD32), compared with a discount of around $12,000/day throughout September, signalling a significant narrowing in the economic incentive to switch into dirty trading.

See why the most successful traders and shipping experts use Kpler