
November 11, 2026
TA is now shut for every December MR arrival
Weaker cash diffs in NWE have pressured transatlantic margins this week, shutting the TA for every December MR arrival despite cheaper freight.
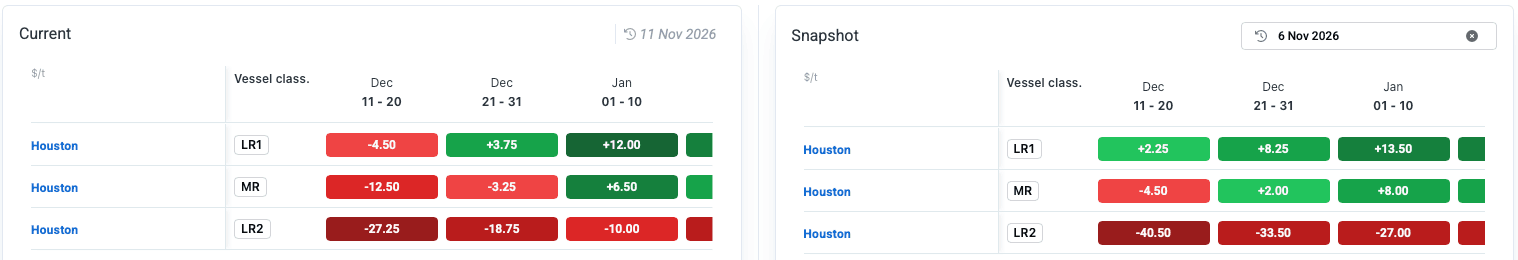
- December shut: Late-December MR margins fell $5.25/t from Friday's close to -$3.25/t this afternoon, with NWE cash diffs shedding $6.75/t. Lower MR rates partly offset this, giving back $3.75/t. Mid-December margins, shut since 5 November, fell further out of the money to -$12.50/t, mostly as cash diffs fell $7.25/t.
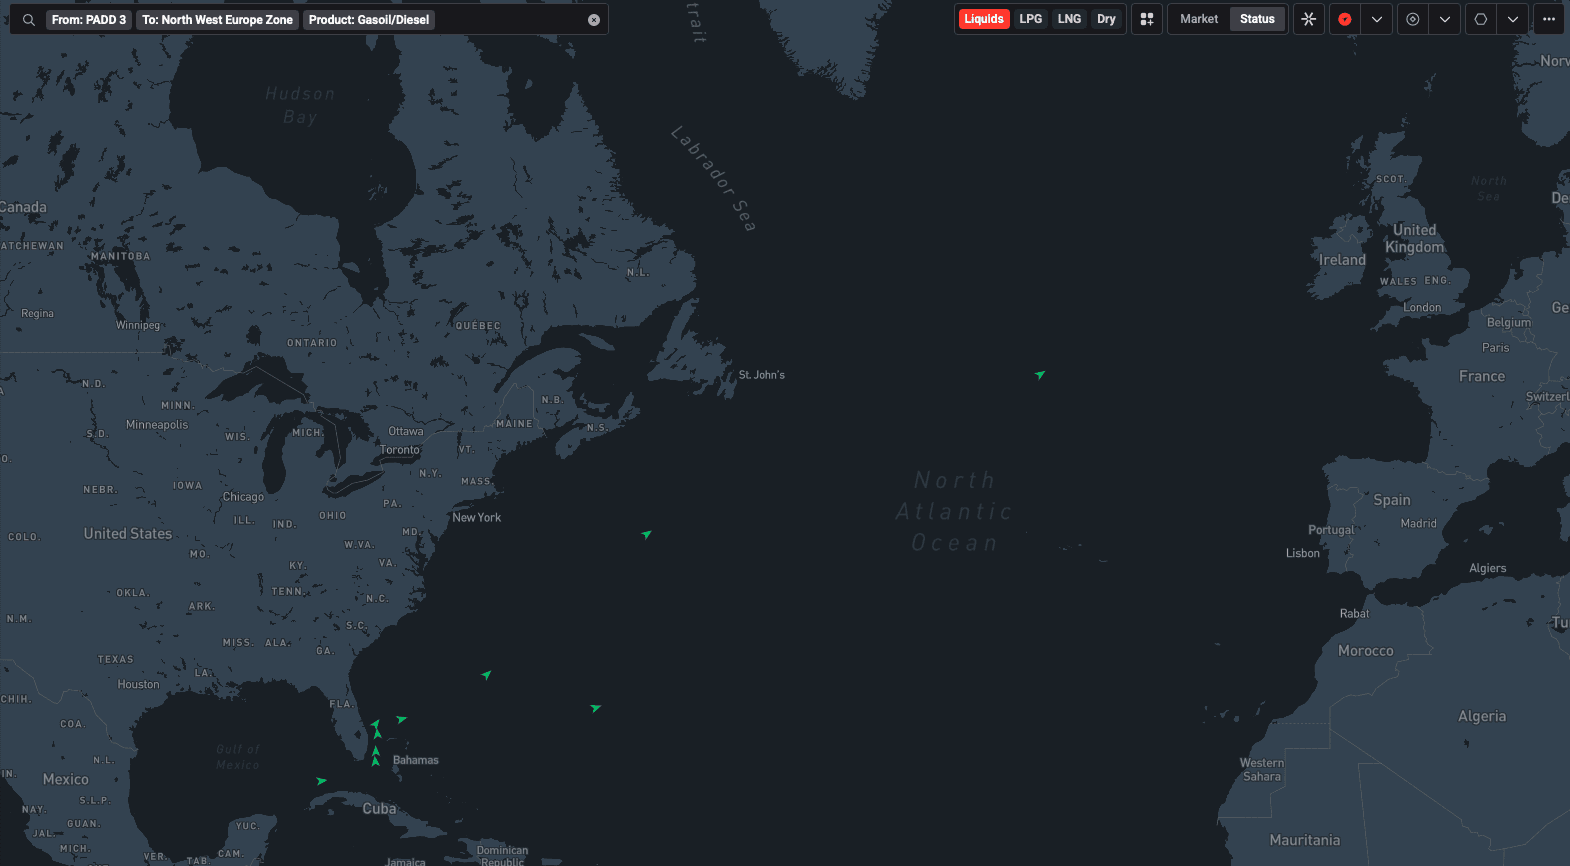
- On the water: The late-October window is still landing. Nine US Gulf MRs are due in NWE between 16 and 28 November, six of them in the week of 23 November, the most since mid-October, after just two over the past three weeks.
- Looking ahead: The late-November arrivals, combined with ongoing SPR releases, should keep NWE cash diffs under pressure into early December. With US Gulf MR tonnage supply pointing to downward pressure on rates, freight is the likelier lever to reopen the arb. A 4% fall in forward MR freight for the 21-31 December window, to around 385WS from 400WS, would reopen it on its own.
NWE arbitrage margins: 11-Nov 15:00UTC vs 6-Nov 18:30UTC
Source: Kpler
PADD3 to NWE gasoil/diesel laden vessels
Source: Kpler
Access Kpler's Arbitrage tool for your team
- Import and export views to compare supply origins and competing destinations across forward windowdws
- A scenario builder to test physical differentials, freight and costs and see the economics update immediately

See why the most successful traders and shipping experts use Kpler
Request a demo